How to Maintain Oversight of Autonomous Finance Workflows
A practical framework for introducing automated or agent-driven treasury workflows without losing human accountability, covering permissions, limits, approvals, exception queues, kill switches and audit logs.

Autonomous finance can reduce the manual work involved in treasury management, vendor payouts, payroll and liquidity transfers. A workflow might prepare a payment batch, choose a settlement rail, convert fiat to USDC or USDT, or rebalance funds between approved accounts.
Automation does not remove the finance team's responsibility for the outcome. The objective is to let systems execute routine instructions while people retain control over policy, exceptions and material transactions.
That requires more than a final approval button. Effective finance oversight combines scoped permissions, transaction limits, approval controls, destination allowlists, exception queues, monitoring, kill switches and complete audit logs.
Start by defining what the workflow may do
Do not give an automated workflow broad access to a treasury balance and then rely on monitoring to catch mistakes. Start with the narrowest set of permissions required for its task.
Define the scope across several dimensions:
- Action: prepare, approve, convert, transfer, cancel or reconcile.
- Assets: for example, USDC only rather than every asset held by the company.
- Networks: such as Base and Ethereum, excluding unsupported or unnecessary chains.
- Destinations: approved bank accounts, wallets, vendors or employees.
- Value: maximum amount per transaction, day and month.
- Time: permitted operating hours or payment dates.
A payroll workflow, for example, might be allowed to prepare USDC payments on Base to employees in an approved payroll file. It should not automatically gain permission to send USDT on Tron, change beneficiary wallets or move the company's reserve balance.
Stablerail supports corporate USDC and USDT treasury operations across networks including Ethereum, Base, Arbitrum, Polygon, Tron, BNB Chain, Optimism and Solana. Network access should be enabled according to the workflow's actual purpose, not simply because it is available.
Use limits and approval thresholds together
Transaction limits place a hard boundary on automation. Approval thresholds determine when a person must become involved. These controls solve different problems and should be used together.
| Control | Example policy | Purpose |
|---|---|---|
| Per-payment limit | Maximum €5,000 equivalent | Limits the impact of one incorrect instruction |
| Daily aggregate limit | Maximum €25,000 across all payments | Stops many small payments bypassing oversight |
| Approval threshold | CFO approval above €10,000 | Escalates material transactions |
| Velocity limit | No more than 50 payments per hour | Detects loops and abnormal batch activity |
| Balance floor | Keep at least $100,000 in the operating vault | Prevents automation from draining required liquidity |
These figures are illustrative. Thresholds should reflect the company's payment volumes, liquidity needs and risk tolerance.
Pay particular attention to cumulative activity. An agent that cannot send more than $5,000 per payment could still send $100,000 through 20 transactions unless an aggregate or velocity limit also applies.
Separate preparation from approval
For higher-risk workflows, let automation assemble and validate a transaction while a person authorizes execution. A prepared payment should show the amount, asset, network, destination, expected fees and business reference before approval.
Self-custodial MPC vaults and quorum signing can enforce this separation at the treasury level. MPC, or multi-party computation, distributes signing authority so that one credential does not control the wallet. Quorum signing requires the configured number of authorized parties to approve a transaction.
For practical batch payment mechanics, see stablecoin payouts.
Restrict destinations with allowlists
An allowlist is a set of destinations that a workflow may use. It can include verified wallet addresses, company bank accounts and established vendor accounts.
Changing an allowlist should be treated as a separate, higher-risk action. Recommended safeguards include:
- Independent approval for adding or editing a destination.
- Wallet and sanctions screening before activation.
- A delay before a newly added destination can receive funds.
- Clear ownership and business-purpose records.
- Alerts when beneficiary details differ from previous invoices or payroll files.
Allowlisting is particularly important on public blockchains because transfers generally cannot be reversed. Confirm both the address and network: the same-looking asset may exist on several networks, but the receiving party may support only one of them.
Route uncertainty into an exception queue
A well-designed workflow should stop when information is incomplete or contradictory. It should not guess.
Send a transaction to an exception queue when:
- The amount exceeds a threshold or differs materially from payment history.
- A wallet or beneficiary is new, changed or fails screening.
- The invoice is duplicated, missing or does not match the payment request.
- The selected asset or network is not approved for that counterparty.
- Estimated fees or conversion costs exceed policy limits.
- The treasury balance would fall below its required floor.
Each exception needs an owner, reason code, timestamp and resolution. Finance teams should also track queue age. A control that pauses questionable payments is useful, but unresolved exceptions can still cause late payroll, vendor disruption or duplicate manual work.
Monitor execution, settlement and reconciliation
Approval is not the end of the workflow. Monitoring should cover whether the transaction was submitted, settled and reconciled against the underlying obligation.
Settlement timing depends on the rail. Onchain transfers may confirm quickly but vary by network conditions. SEPA Instant is designed for euro payments within seconds and operates around the clock, subject to participating institutions and applicable limits. ACH payments typically take longer and may be returned after submission. SWIFT timing depends on correspondent banks, currencies and cut-off times.
Do not let an automation system interpret “submitted” as “paid.” Track explicit states such as prepared, approved, broadcast or sent, confirmed or settled, failed, returned and reconciled.
Monitoring should alert finance teams to failed transactions, repeated retries, unusual payment velocity, large deviations from forecast and unreconciled balances. Use wallet checking tools when reviewing new or changed blockchain destinations.
Implement kill switches at several levels
A kill switch should stop new activity without requiring the team to redesign the workflow during an incident. It should be tested before production use.
Useful levels include:
- Workflow level: pause one payroll, vendor or rebalancing process.
- Asset or network level: stop USDT or disable a specific chain.
- Destination level: block a compromised beneficiary.
- Account level: stop all outgoing activity from a vault or fiat account.
Document who may activate the switch, how access is secured and what must happen before operations resume. Preserve pending transactions for review rather than automatically releasing them when the workflow restarts.
Keep complete audit logs and evidence
Audit logs should make every automated decision reconstructable. Record the original request, policy version, data inputs, validations, approvals, edits, timestamps, identities, transaction identifiers, fees, exchange details and final settlement status.
For agent-driven activity, also retain the agent or workflow version and the reason or rule used for each decision. Avoid relying only on free-form explanations. Structured reason codes are easier to review and test.
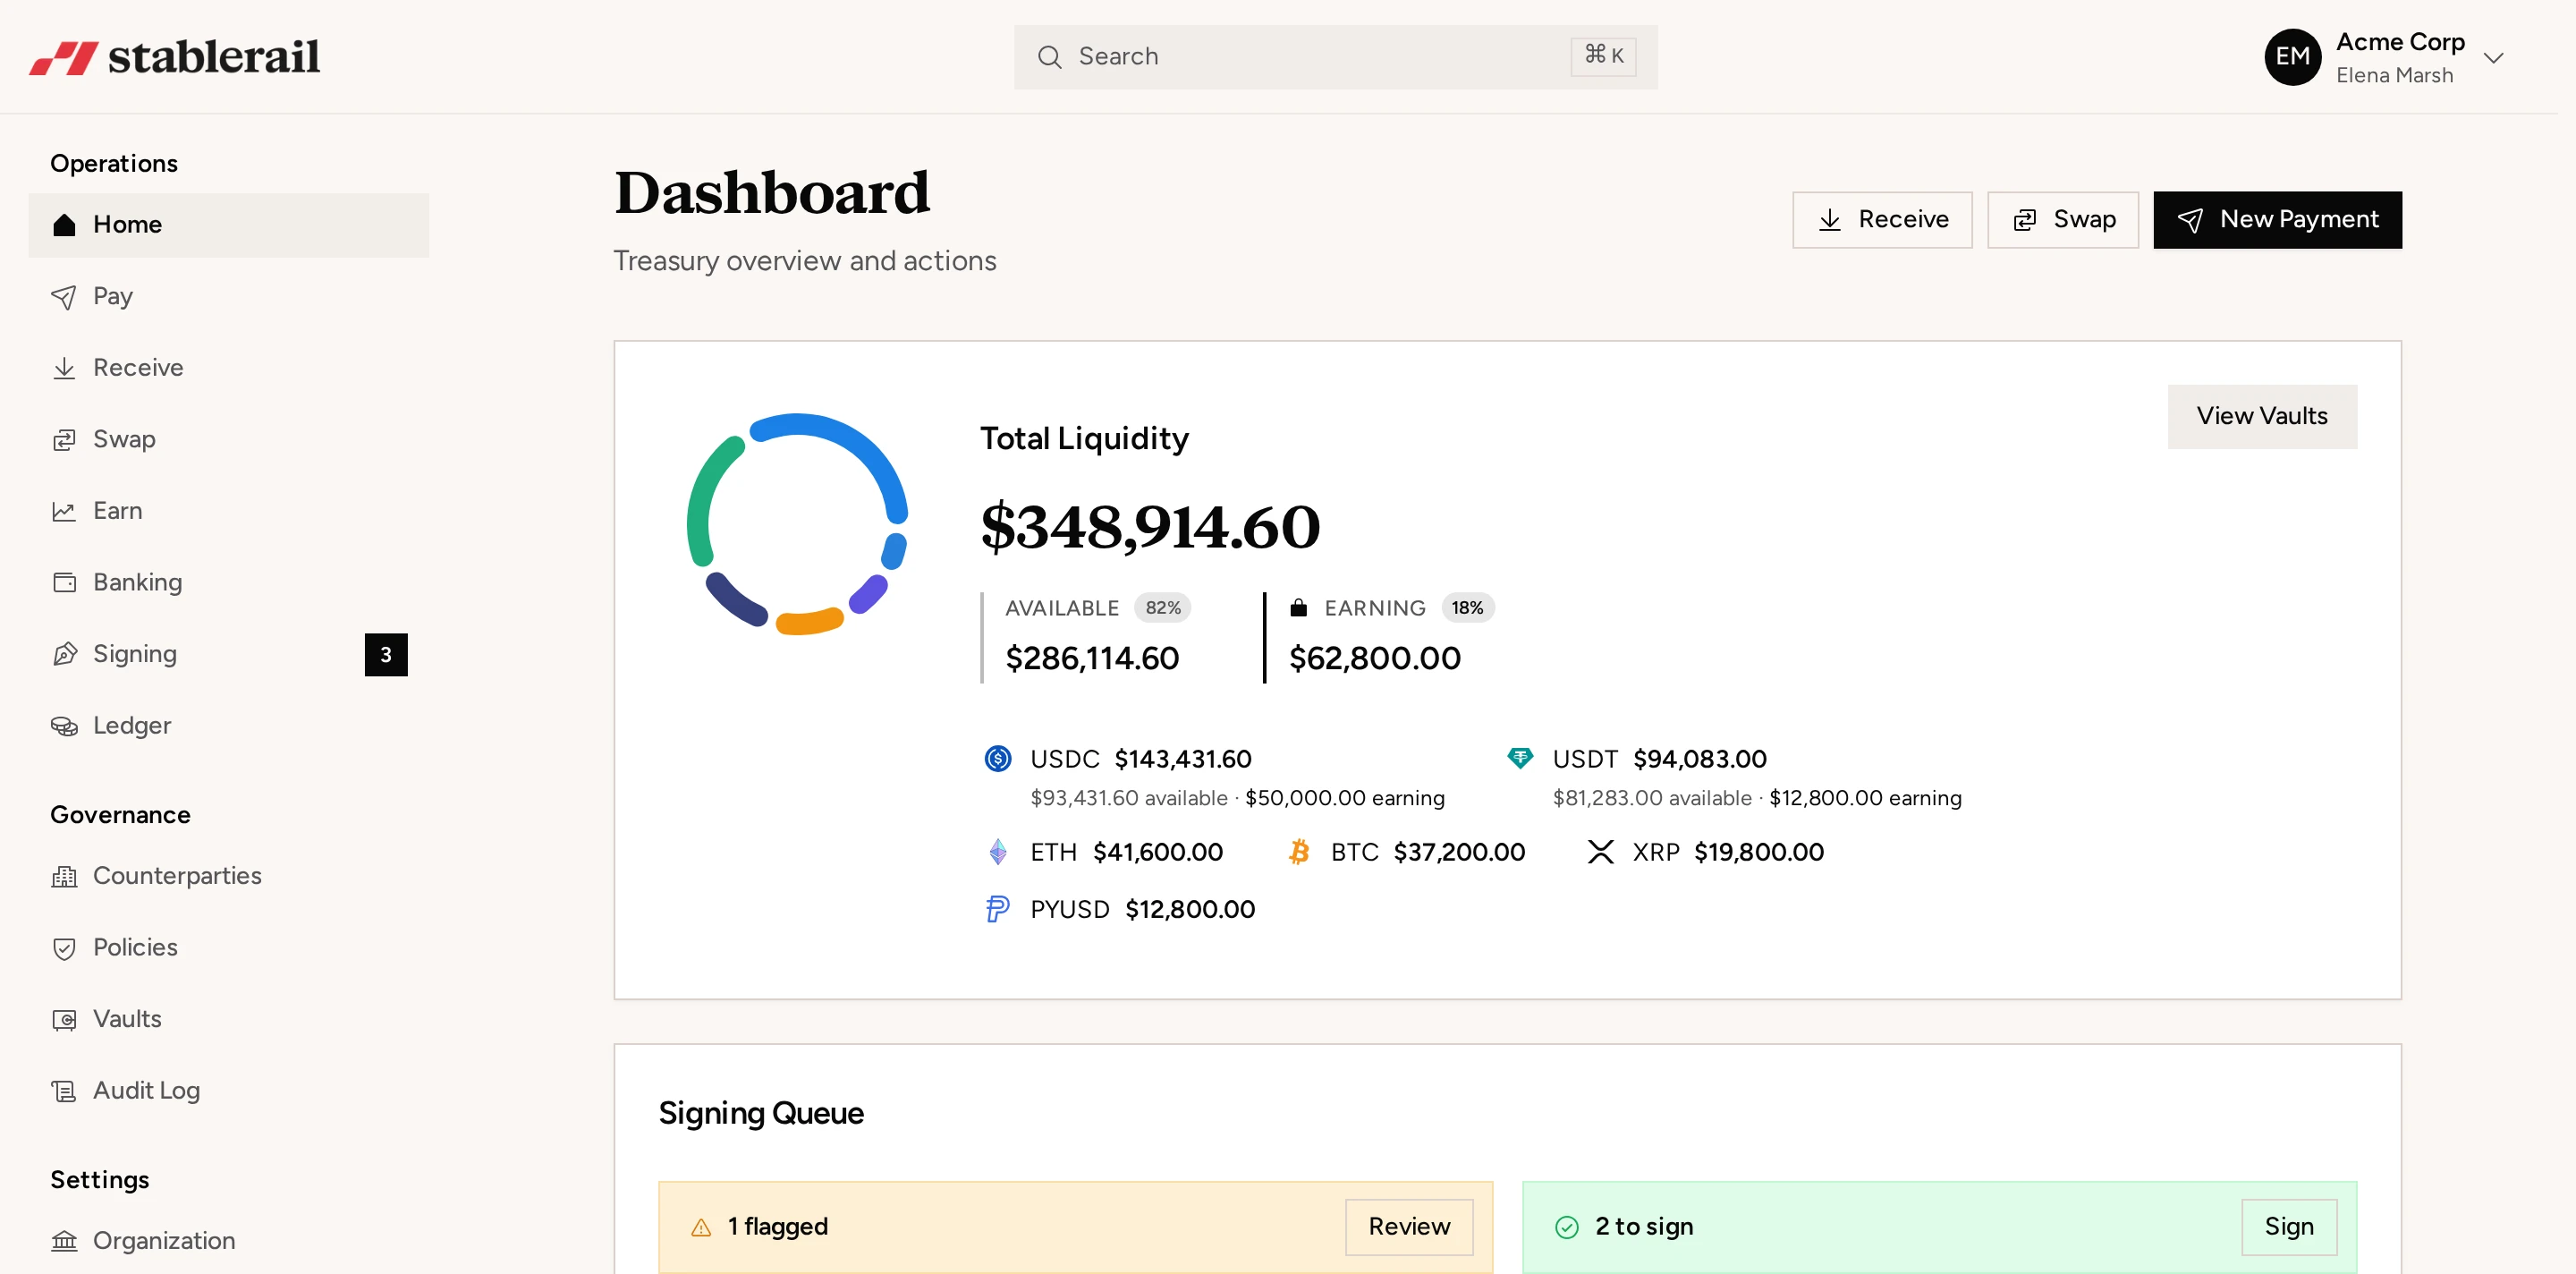
Stablerail's audit trail and evidence packs can support operational review, while approval limits, allowlists, sanctions screening and wallet screening provide controls around treasury activity. The finance team should still maintain the source documents—such as invoices, payroll files and contracts—that establish the business purpose.
Roll out automation in controlled stages
Begin with read-only tasks such as balance monitoring and reconciliation suggestions. Next, allow the workflow to prepare transactions without sending them. After testing, permit low-value payments to established destinations, with material or unusual activity requiring human approval.
Review performance after each stage: exception rates, failed payments, approval delays, limit breaches and reconciliation differences. Expand autonomy only when the workflow behaves consistently and the team can stop it quickly.
The central principle is simple: automation may execute policy, but people must own the policy. Clear boundaries, strong approval controls and reliable audit logs allow autonomous finance workflows to save time without obscuring accountability.
Finance writers covering stablecoin treasury, payments, compliance, and risk controls.
More about the Stablerail team- Stablecoin treasury managementApprovals, limits, yield and reporting on one balance.
- Stablecoin payoutsBatch contractor and vendor payments with screening.
- USDT vs USDCWhich stablecoin your company should settle in.
- Stablecoin finance glossaryMPC, off-ramp, travel rule and the rest, in plain English.
- Product updatesEverything we ship, month by month.