GBP Business Payments: Faster Payments, CHAPS and Bacs Compared
Compare Faster Payments, CHAPS and Bacs by timing, limits, cost and use case—and learn what a GBP business account should provide when your company also holds USDC or USDT.

UK companies have three main domestic rails for sending pounds: Faster Payments, CHAPS and Bacs. They all move GBP between UK accounts, but they serve different operational needs.
Faster Payments is usually the default for urgent, everyday transfers. CHAPS is designed for high-value, time-critical payments. Bacs is best suited to planned, high-volume payments such as payroll and supplier runs.
For a company that also holds USDC or USDT, the choice of rail is only part of the workflow. A useful GBP business account should also make it straightforward to receive pounds, convert between fiat and stablecoins, reconcile transactions and apply approval controls.
Faster Payments, CHAPS and Bacs at a glance
| Rail | Typical timing | Availability | Limits | Typical cost profile | Best suited to |
|---|---|---|---|---|---|
| Faster Payments | Usually seconds or minutes | 24 hours a day, including weekends | Scheme limit up to £1 million, but provider limits may be lower | Usually free or low-cost; provider fees vary | Routine suppliers, refunds and urgent operating payments |
| CHAPS | Same business day if submitted before the provider cutoff | UK business days | No standard scheme-level maximum, although providers may impose limits | Normally a fixed fee; traditional banks often charge around £20–£35 | Large, urgent or completion-critical transfers |
| Bacs Direct Credit | Three-business-day processing cycle | Business-day cycle | Provider and service limits apply | Low per-item cost, often with platform or submission fees | Payroll, contractors and large scheduled payment batches |
Timings and fees in this table are market conventions rather than guaranteed terms. Each bank or payment provider can set its own cutoff times, transaction limits and pricing.
Faster Payments: the everyday option
Faster Payments is the main rail for routine UK account-to-account transfers. Payments are normally credited within seconds, although some can take longer if a bank performs additional fraud or compliance checks.
The service operates continuously, so a payment can be sent in the evening, at weekends or on a bank holiday. That makes it useful when a supplier needs to be paid outside conventional banking hours.
The scheme supports payments of up to £1 million, but that does not mean every business can send £1 million in one transaction. A provider may apply lower limits based on the account, user role, payment channel or risk review. Daily aggregate limits can also apply.
Use Faster Payments for:
- Routine supplier and contractor payments
- Urgent refunds or expense reimbursements
- Moving cash between the company’s own UK accounts
- Funding an exchange or stablecoin conversion workflow
- Paying invoices that fall within the provider’s transaction limit
Before relying on Faster Payments for a large invoice, check both the per-payment limit and the daily limit. Splitting a payment into several transfers may create reconciliation problems and can trigger additional review.
CHAPS: for high-value, time-critical transfers
CHAPS is the UK’s same-day high-value payment system. Unlike Faster Payments, it operates on business days and is subject to submission cutoffs. The provider’s customer cutoff will normally be earlier than the underlying system’s closing time.
CHAPS does not have a standard scheme-level payment maximum. It is commonly used when the value is too high for Faster Payments or when completion on a specific business day is essential. Examples include property transactions, acquisitions, treasury movements and large supplier settlements.
Payments are generally final once processed. Finance teams should therefore verify the beneficiary name, sort code, account number and payment purpose before approval. A recall may be requested after an error, but recovery is not guaranteed.
Use CHAPS when:
- The amount exceeds your Faster Payments limit
- The beneficiary must receive cleared funds that business day
- A contract or completion process requires CHAPS
- The cost of a delayed payment is greater than the transaction fee
CHAPS is usually more expensive than Faster Payments. Traditional UK banks commonly charge a fixed fee in the region of £20–£35, although digital providers may price it differently. Check whether inbound CHAPS payments, outbound payments or both carry fees.
Bacs: built for planned payment runs
Bacs is slower but efficient for predictable, high-volume payments. Bacs Direct Credit is widely used for salaries, pensions, contractor payments and recurring supplier runs. Direct Debit, a separate Bacs service, allows an authorised organisation to collect money from customer accounts.
A standard Bacs Direct Credit follows a three-business-day cycle:
- Day 1 — input: The payment file is submitted before the applicable cutoff.
- Day 2 — processing: Bacs processes the instructions.
- Day 3 — entry: Funds are debited from the sender and credited to recipients.
Weekends and UK bank holidays do not count as processing days. A payroll file submitted too late on Friday may therefore miss a Monday payment date.
Bacs can offer a low per-payment cost, but the full price may include access, software, bureau or file-submission charges. Businesses without direct Bacs sponsorship often access the rail through a bank, payroll provider or approved bureau.
For stablecoin-funded contractor or payroll workflows, decide early whether recipients will be paid in GBP or stablecoins. If GBP is required, convert the necessary USDC or USDT with enough time for settlement and the Bacs submission cycle. For on-chain recipients, a dedicated crypto payroll workflow may be more appropriate.
How to choose the right UK payment rail
A simple treasury policy can route payments by urgency, value and volume:
- Routine and urgent payments within account limits: use Faster Payments.
- Large transfers that must arrive today: use CHAPS before the provider cutoff.
- Scheduled payroll or high-volume batches: use Bacs and submit the file in advance.
- International GBP payments: check whether local UK rails are available; otherwise SWIFT may be required.
Do not choose solely on headline transaction fees. Include staff time, payment-file preparation, failed-payment handling, foreign-exchange costs and the impact of missed cutoffs.
What a GBP business account should provide
A company managing both pounds and stablecoins needs more than an account number. At minimum, assess whether the account provides:
- A UK sort code and account number in the company’s name or clearly allocated to it
- Inbound and outbound Faster Payments, CHAPS and Bacs capabilities
- Published transaction limits, fees and cutoff times
- Multi-currency balances and transparent conversion pricing
- On-ramps and off-ramps between GBP and USDC or USDT
- Batch payments for suppliers, contractors and payroll
- Downloadable statements, transaction references and reconciliation data
- Approval limits, multiple approvers and beneficiary allowlists
- Sanctions and wallet screening for fiat-to-stablecoin workflows
- An audit log showing who created, approved and released each payment
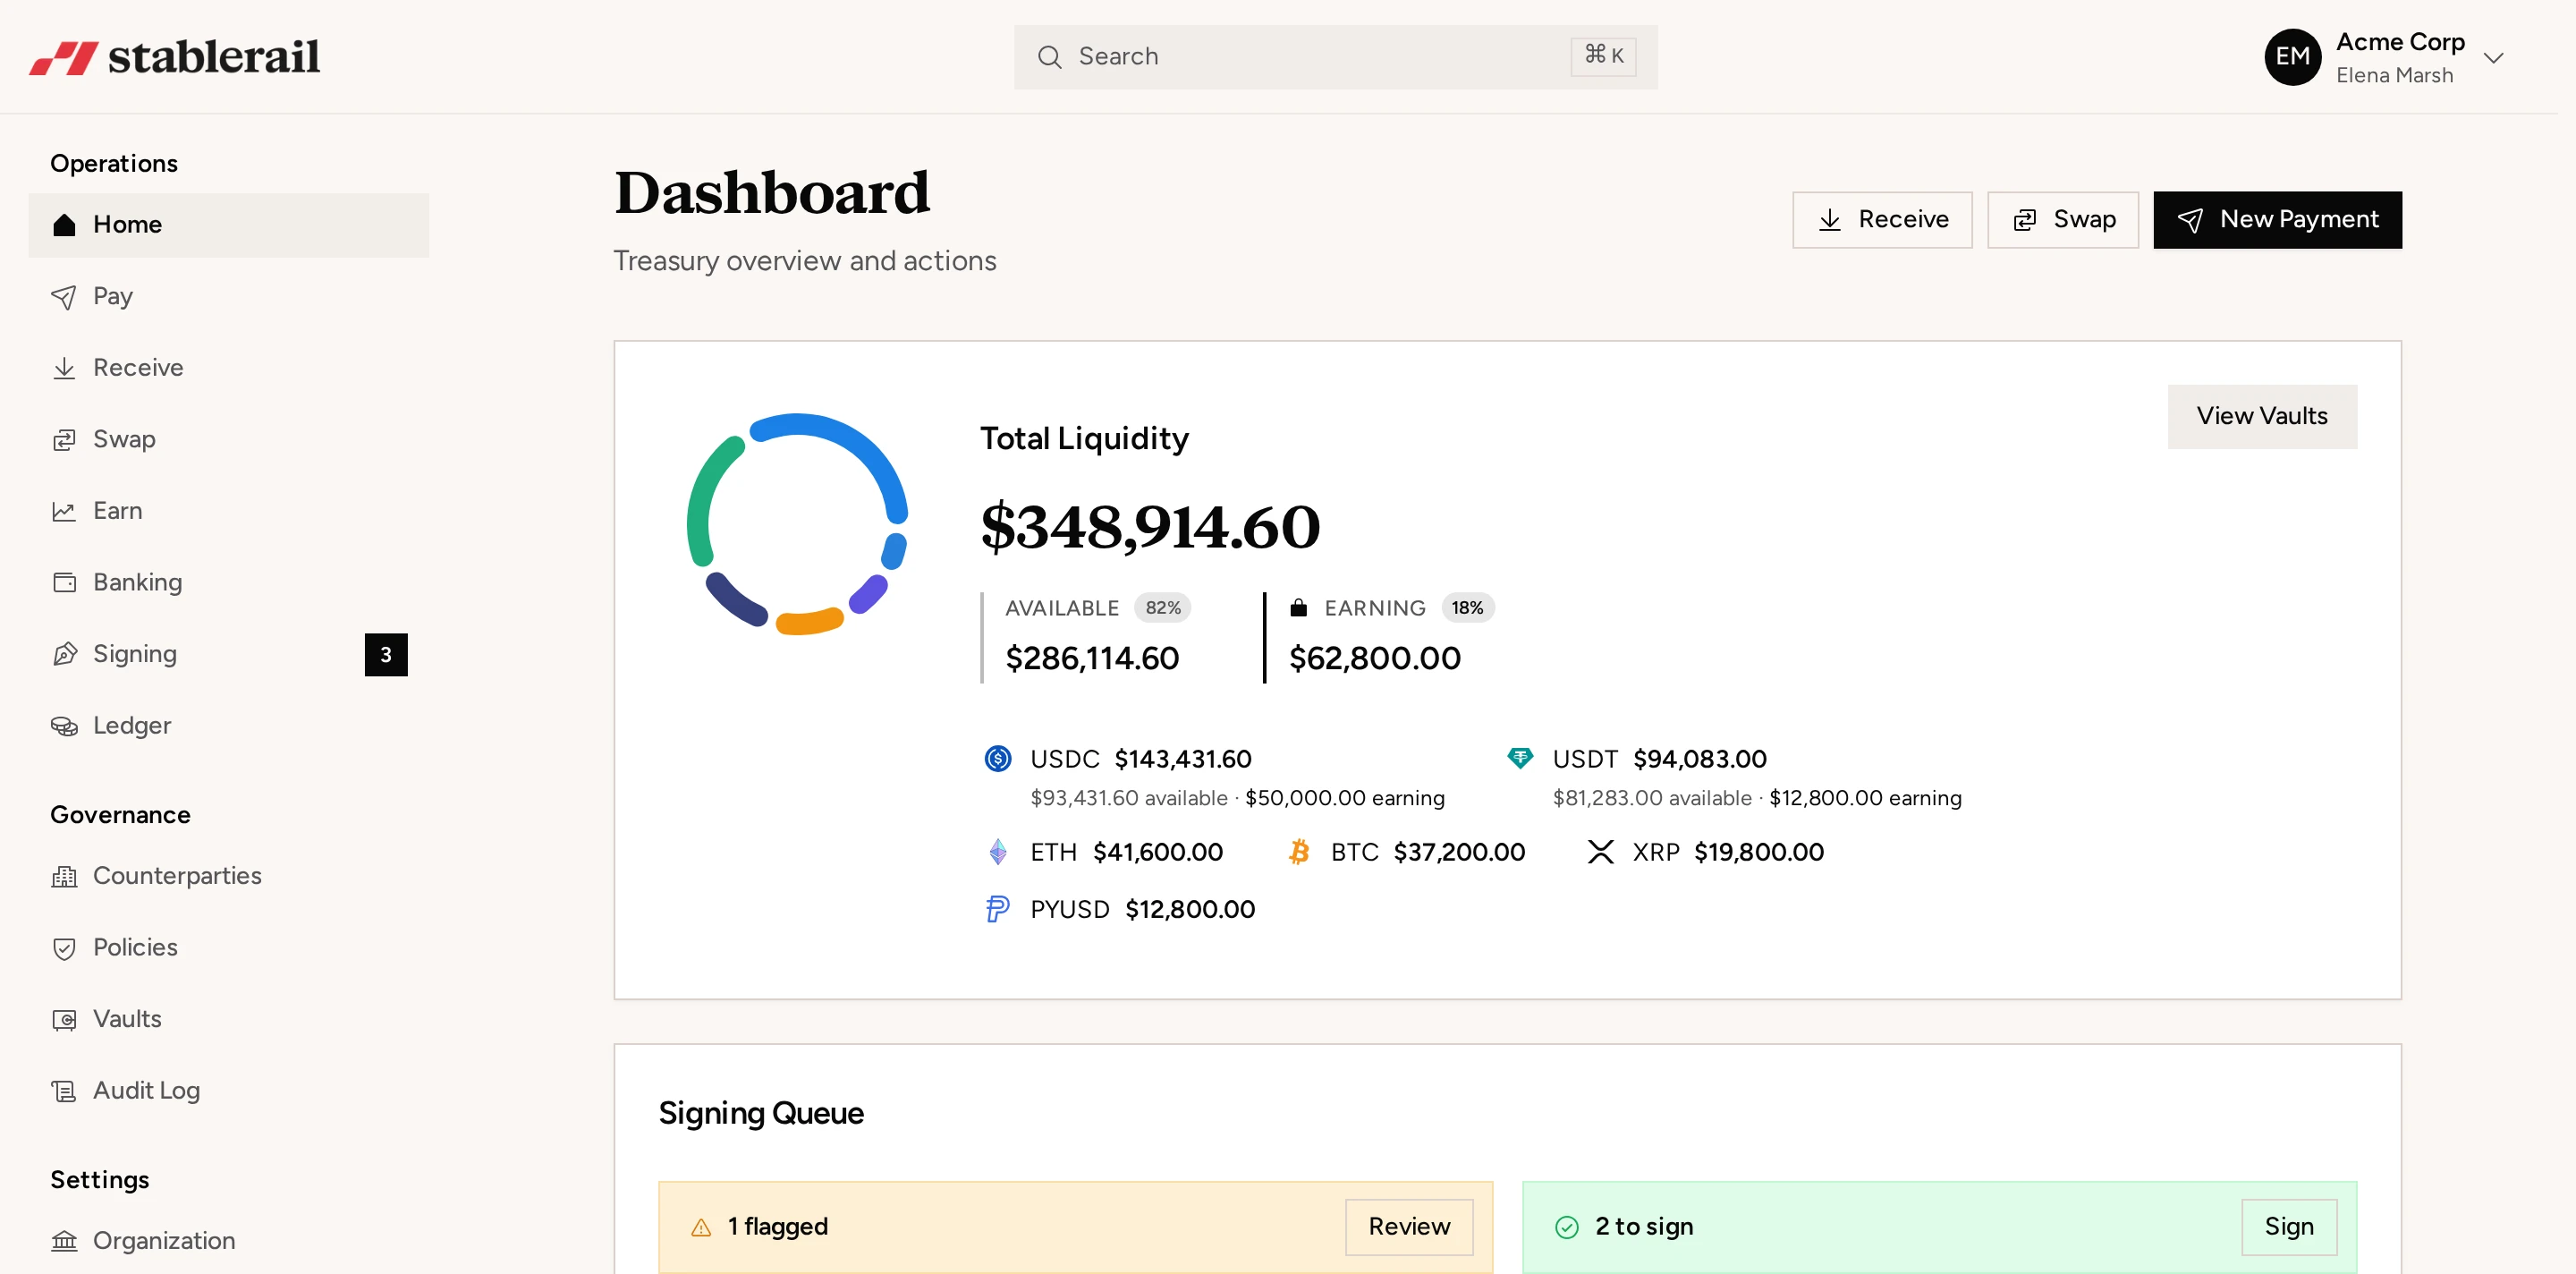
Stablerail combines GBP payment rails with corporate stablecoin treasury tools, including self-custodial MPC vaults, quorum signing and payouts across supported blockchain networks. Finance teams can use the same operating environment to manage fiat balances, stablecoin conversions and batch stablecoin payouts.
Check the legal structure behind any account as part of onboarding. Funds held through a payment or electronic-money institution may be safeguarded rather than protected by the UK Financial Services Compensation Scheme. The provider should explain which entity holds the funds and what protection applies.
Plan around conversion and settlement
When USDC or USDT is the source of funds, work backwards from the GBP payment deadline. Allow time for blockchain confirmations, wallet screening, conversion, fiat settlement and the chosen rail’s cutoff.
A Faster Payment may arrive within minutes once pounds are available, but that does not mean the complete stablecoin-to-GBP workflow is instantaneous. Likewise, a Bacs payroll run still requires three business days after the payment file is accepted.
Before committing to a provider, compare the complete corridor cost: stablecoin withdrawal or network fees, conversion spread, stated on/off-ramp pricing and the domestic payment fee. For companies holding USDC, a dedicated USDC business account workflow can connect stablecoin treasury balances with day-to-day fiat operations.
Finance writers covering stablecoin treasury, payments, compliance, and risk controls.
More about the Stablerail team- Stablecoin treasury managementApprovals, limits, yield and reporting on one balance.
- Stablecoin payoutsBatch contractor and vendor payments with screening.
- USDT vs USDCWhich stablecoin your company should settle in.
- Stablecoin finance glossaryMPC, off-ramp, travel rule and the rest, in plain English.
- Product updatesEverything we ship, month by month.