USDT business account: what your company needs beyond an exchange login
Learn how to evaluate a USDT business account for custody, approvals, Tron and Ethereum transfers, fiat off-ramps, reconciliation and corporate controls.
A USDT business account should give finance teams controlled access to company funds, not merely a place to trade tokens. It should support the required USDT networks, separate payment creation from approval, screen destination addresses, document every transfer and provide a reliable fiat off-ramp. The right setup also produces records that controllers and auditors can reconcile without relying on shared credentials or screenshots.

An exchange login can be sufficient for occasional USDT purchases, but it is usually a poor operating model for corporate treasury. Day-to-day use requires defined authority over funds, network-specific payment controls, approval evidence, counterparty records and a tested route back to fiat. These requirements matter whether the company receives USDT from customers, pays international suppliers or holds it as working capital.
Exchange login versus USDT business account
The main distinction is not whether the product can receive, hold and send USDT. It is whether the setup fits the company’s treasury, accounting and internal-control processes.
| Requirement | Typical exchange login | Business treasury setup |
|---|---|---|
| Primary purpose | Trading and asset conversion | Controlled holding, payments and conversion |
| Custody | The exchange generally controls the private keys | May use institutional custody or a self-custodial signing arrangement |
| Payment authority | Often tied to account roles and withdrawal permissions | Payment creation, approval and signing can be separated |
| Destinations | Saved addresses and exchange withdrawal checks | Approved beneficiaries, address controls and pre-send screening |
| Networks | Availability determined by the exchange | Required asset and network pairs are selected deliberately |
| Fiat conversion | Trade USDT, then request a bank withdrawal | Documented conversion and payout workflow linked to corporate accounts |
| Accounting evidence | Trading and withdrawal history | Transaction references, approvals, beneficiary data and exportable evidence |
An exchange may remain useful for liquidity or particular trading pairs. The decision is whether it should also be the primary operating account for supplier payments and working capital. Finance teams should review the exchange’s withdrawal rules, account-recovery process and legal terms rather than assuming a corporate login creates treasury-grade controls.
Specify the exact USDT network
USDT is issued on multiple blockchains. Therefore, “send USDT” is not a complete payment instruction: the asset, network and destination must all match. A transfer sent on the wrong network may not appear at the destination, and recovery can be slow, expensive or impossible.
| Operational question | USDT on Tron | USDT on Ethereum |
|---|---|---|
| Token format | TRC-20 | ERC-20 |
| Common address presentation | Usually begins with “T” | Usually begins with “0x” |
| Network resource | TRX, bandwidth and energy affect transfer execution | ETH is used to pay gas |
| Cost behavior | Depends on available network resources and wallet handling | Gas cost varies with network demand |
| Key failure mode | The recipient supports USDT but not TRC-20 deposits | The recipient does not support ERC-20 deposits or the sender lacks ETH for gas |
Address appearance is a useful warning signal, but it is not a substitute for checking the receiving platform’s deposit instructions. Finance should record the beneficiary name, asset, network and address as one approved payment record. Do not copy only the address into an invoice or spreadsheet while leaving the network in an email thread.
For a new beneficiary, independently confirm the instructions through a known contact and send a small test payment before releasing the full amount. The test must use the same asset, network and destination as the intended payment. Verify that the recipient has credited it, rather than treating a successful blockchain broadcast as proof that the beneficiary can access the funds.
Network availability can change by provider, account and jurisdiction. Check both deposits and withdrawals: support for receiving USDT on a network does not necessarily mean the provider permits withdrawals on that same network.
Match custody to corporate authority
With a conventional exchange account, the exchange generally holds the private keys and processes withdrawals after the company submits an instruction. The company has contractual access to an account balance but does not directly sign the blockchain transaction.
A self-custodial arrangement gives the company direct responsibility for transaction signing and recovery. Some setups use multi-party computation, or MPC, to distribute signing so that a complete private key does not need to exist on one device. A signing quorum can then require more than one authorised participant before funds move.
Neither model removes operational risk. Custodial users depend on the provider’s access, withdrawal and recovery processes. Self-custodial users must protect signing access, maintain approver availability and test recovery procedures. The correct choice depends on the company’s capabilities and risk tolerance, not on whether one model is described as more “secure” in isolation.
Questions to resolve before funding the account
- Who can create, approve and sign a payment?
- Can one person add a destination and release funds to it?
- How is access removed when an employee changes role or leaves?
- What happens if an approver loses a device or is unavailable?
- Who can change the signing quorum or initiate recovery?
- How often are users, permissions and recovery details reviewed?
Put controls before the blockchain transfer
USDT transfers are generally irreversible once confirmed. Controls are therefore most valuable before signing and broadcast. At minimum, the workflow should separate payment creation from approval, display the network clearly and retain evidence of who authorised the transfer.
Destination screening should also occur before sending. Sanctions and address screening can identify reasons to pause or escalate a payment, but it does not replace counterparty due diligence. Finance still needs to establish who controls the destination, why the payment is being made and whether the supporting invoice is valid.
For each transfer, preserve the legal entity, beneficiary, invoice or payment reference, asset, network, amount, destination address, exchange-rate evidence where applicable, approvals, transaction hash and final status. For batches, retain item-level outcomes so a rejected or failed transfer can be investigated without obscuring successful items.
A transaction hash proves that a blockchain transaction occurred. It does not, by itself, prove the business purpose, the identity of the beneficiary or the accounting treatment.
Plan the fiat off-ramp before receiving USDT
A company receiving USDT may still need fiat for taxes, salaries or suppliers. The off-ramp should be reviewed before funds arrive. A typical flow transfers USDT to an approved conversion route, converts it into the required currency and pays the resulting fiat to a corporate bank account.
| Cost or timing factor | What finance should confirm |
|---|---|
| Conversion | Quoted rate, spread or fee and how long the quote remains valid |
| Blockchain transfer | Who pays the network cost and which token is required for gas |
| Fiat payout | Rail, payout charge, minimum amount and beneficiary requirements |
| Banking deductions | Whether intermediary or recipient-bank fees can be deducted |
| Settlement timing | Cut-off time, compliance review, weekends and destination-bank participation |
| Reconciliation | Reference linking the USDT debit, conversion and fiat credit |
Relevant rails can include SEPA or SEPA Instant for euros, ACH or Fedwire for US dollars, Faster Payments, BACS or CHAPS for sterling, and SWIFT for cross-border transfers. “Instant” or “same day” should not be treated as an unconditional promise: availability depends on participation, cut-offs, compliance checks and beneficiary-bank processing.
Compare the full corridor cost, not only the advertised conversion rate. A narrow spread can be offset by network charges, payout fees or intermediary-bank deductions. Treasury should also test whether the bank account must be held in the same legal name as the verified corporate account.
Prepare for corporate onboarding
Opening a business account normally involves know-your-business checks. Requirements vary by jurisdiction, ownership structure and industry, but companies should be prepared to provide:
- Incorporation documents and a current registry extract
- Constitutional documents and registered address
- Director and beneficial-owner information
- Identity and address evidence for relevant individuals
- A description of products, customers and expected activity
- Source-of-funds or source-of-wealth evidence when requested
- Expected USDT volumes, networks, counterparties and fiat corridors
A clear flow-of-funds explanation can reduce follow-up questions. It should state who sends the company USDT, the commercial reason for using it, where outgoing payments go and which corporate bank accounts will receive converted fiat.
USDT business account selection checklist
- Confirm networks: document the exact USDT networks available for both deposits and withdrawals.
- Define authority: map payment creation, approval, signing, recovery and user administration.
- Test a destination: verify instructions independently and complete a small payment on the intended network.
- Review total costs: include network, conversion, payout and potential banking charges.
- Test the off-ramp: complete a representative USDT-to-fiat conversion before relying on it for a deadline.
- Export evidence: confirm accounting can retrieve approvals, references, transaction hashes and conversion records.
- Document continuity: record procedures for staff departures, lost access and unavailable approvers.
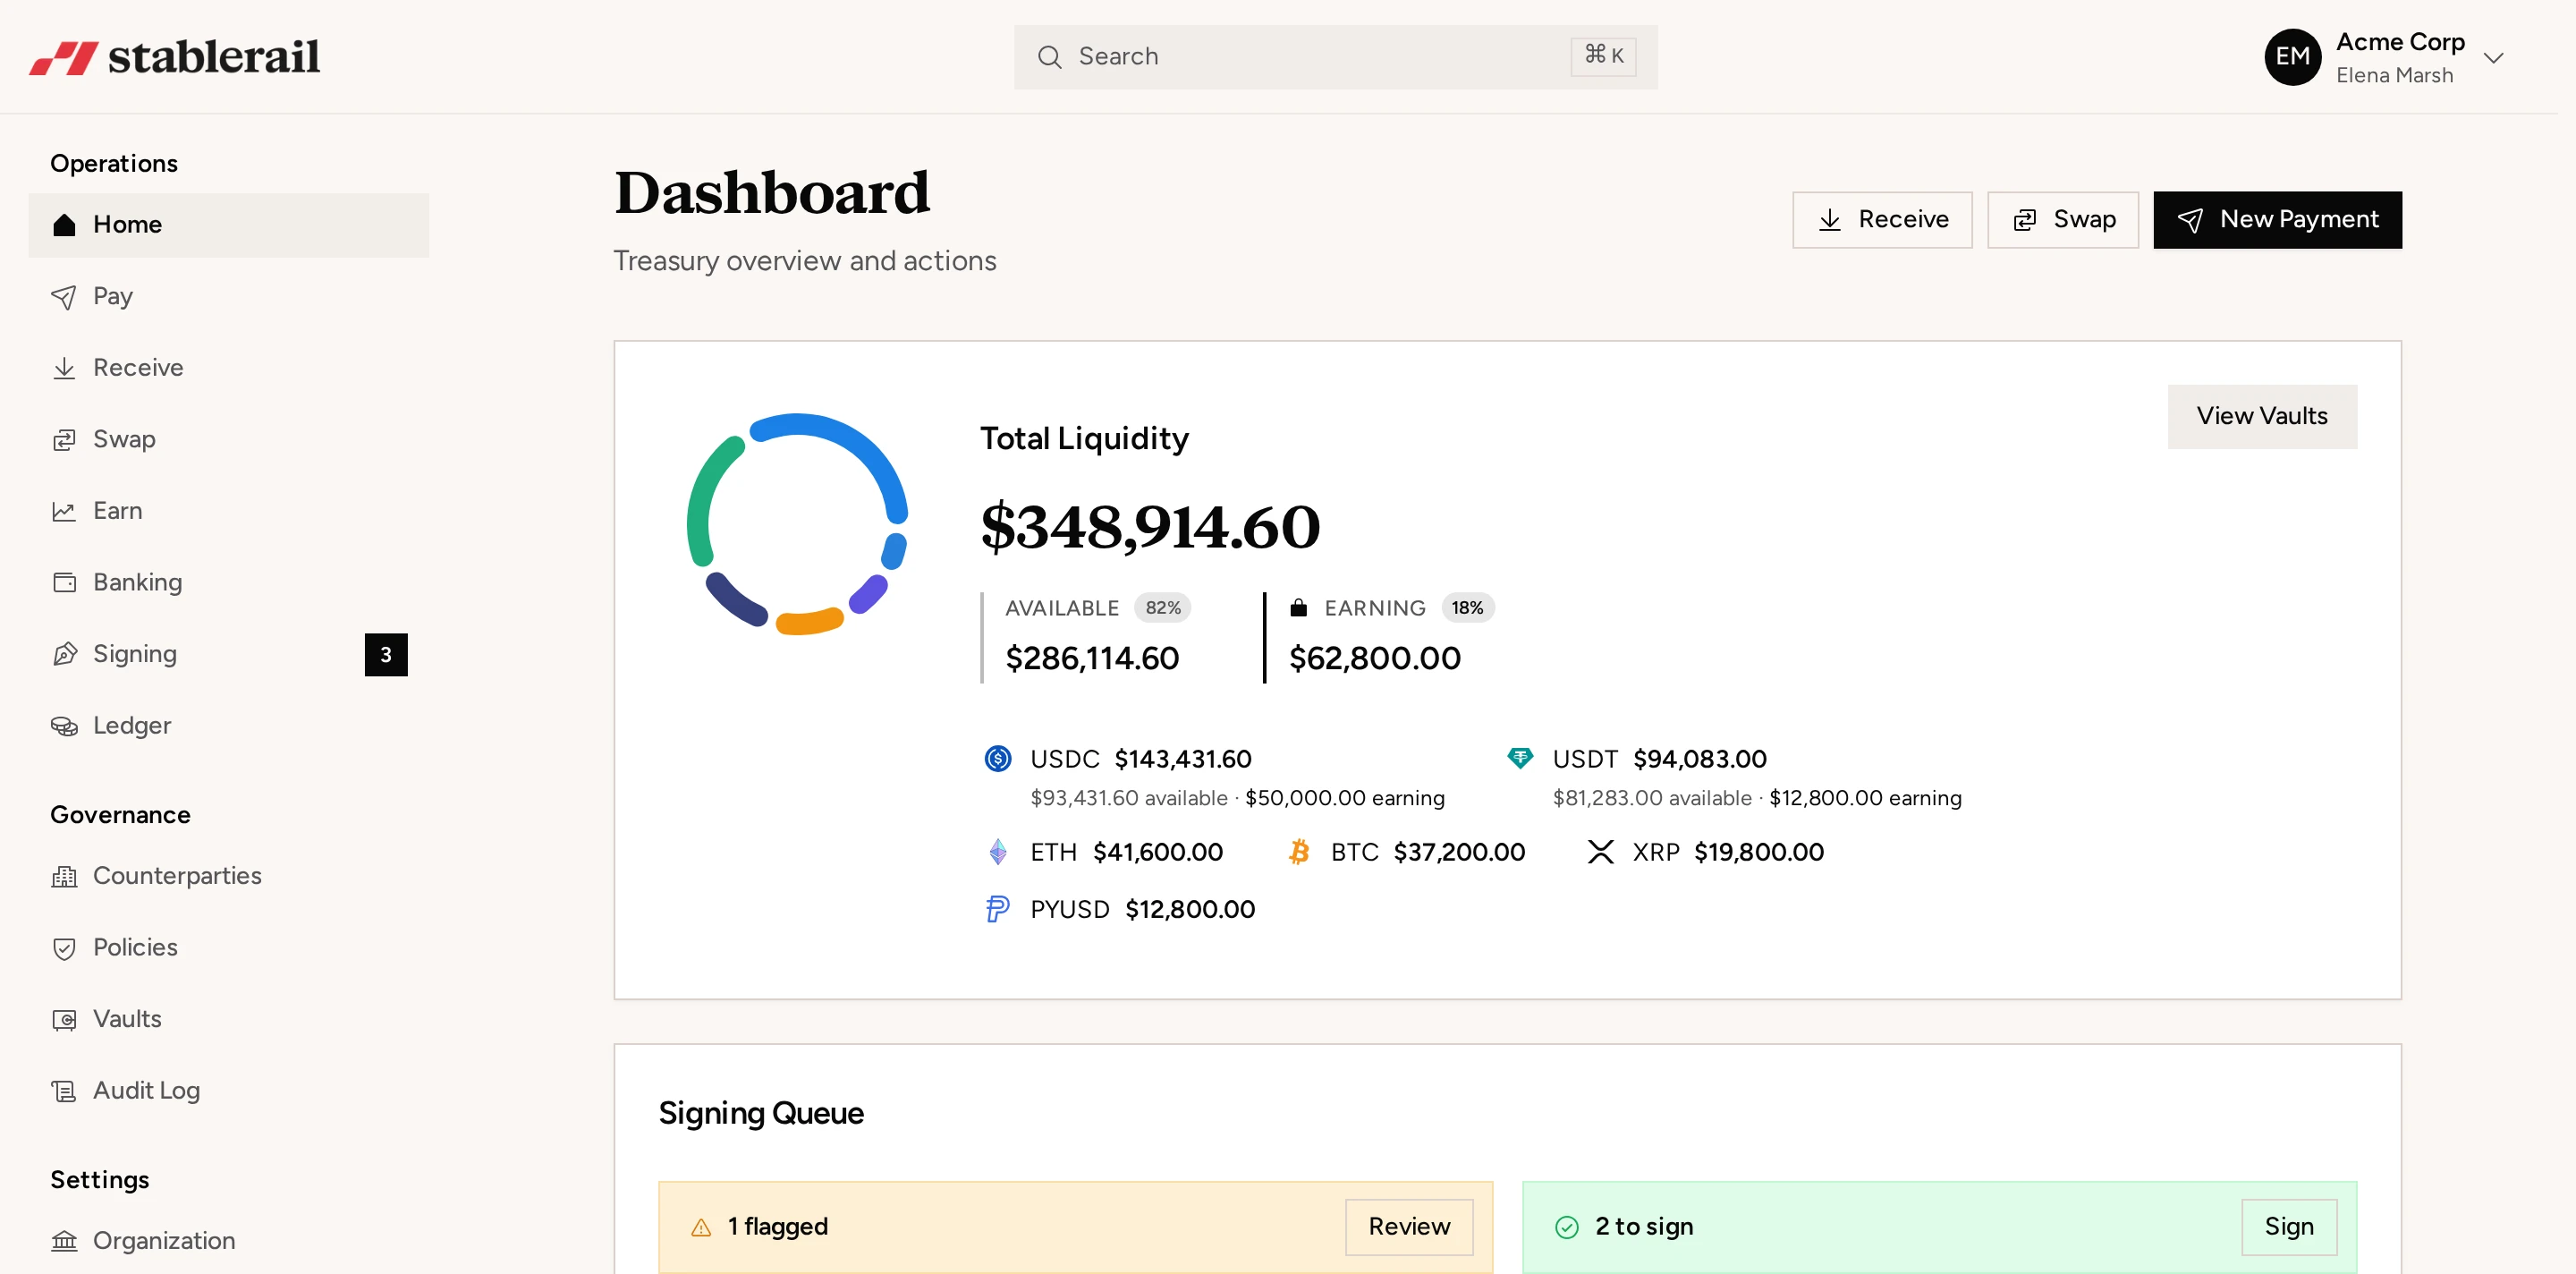
The best setup is the one finance can operate, control and reconcile consistently. Stablerail brings company USDC and USDT operations into a corporate treasury workflow with approvals and signing quorum, pre-send sanctions and address screening, global payouts, fiat conversion and exportable audit evidence. Whatever provider is selected, the control design should be agreed before material funds are deposited.
Frequently asked questions
Can a company hold USDT in a business account?
Yes, subject to the provider’s jurisdiction, industry and onboarding requirements. The company should use an account opened in its legal name and document who can access, approve and reconcile the funds.
Is a crypto exchange account enough for business USDT payments?
It may be enough for occasional purchases or conversions, but it can be inadequate for recurring treasury operations. Finance teams often need separated approvals, destination controls, pre-send screening and accounting evidence beyond a standard trading and withdrawal interface.
What is the difference between TRC-20 USDT and ERC-20 USDT?
TRC-20 USDT moves on Tron, while ERC-20 USDT moves on Ethereum. They use different networks and fee mechanisms, so the sender must confirm that the recipient supports the exact network before transferring funds.
How does a business convert USDT to a bank account?
The business sends USDT through an approved conversion route, converts it into fiat and requests payment to a verified corporate bank account. Before relying on the route, confirm the exchange rate, fees, banking rail, cut-off times and required reconciliation records.
What records should a company keep for USDT payments?
Keep the business purpose, invoice reference, beneficiary, asset, network, destination address, amount, approvals, transaction hash and final status. If USDT is converted to fiat, also retain the conversion rate, fees and bank-payment reference.
Finance writers covering stablecoin treasury, payments, compliance, and risk controls.
More about the Stablerail team- Stablecoin treasury managementApprovals, limits, yield and reporting on one balance.
- Stablecoin payoutsBatch contractor and vendor payments with screening.
- USDT vs USDCWhich stablecoin your company should settle in.
- Stablecoin finance glossaryMPC, off-ramp, travel rule and the rest, in plain English.
- Product updatesEverything we ship, month by month.