How Stablecoin Spend Management Works for Business Teams
Learn how businesses fund corporate cards from USDC or USDT, set employee and merchant limits, capture receipts, categorize expenses and reconcile card spending.

Stablecoin spend management connects a company’s USDC or USDT treasury to day-to-day business expenses. Instead of sending stablecoins to employees or asking them to pay personally and claim reimbursement, finance teams can issue corporate cards funded from the company’s treasury balance.
The practical workflow is familiar: issue virtual or physical cards, assign limits, restrict merchant types, collect receipts and reconcile transactions. The main difference is funding. Stablecoins must be converted into the card’s settlement currency at some point in the process, and finance needs a record of both the stablecoin movement and the resulting card expense.
How the funding flow works
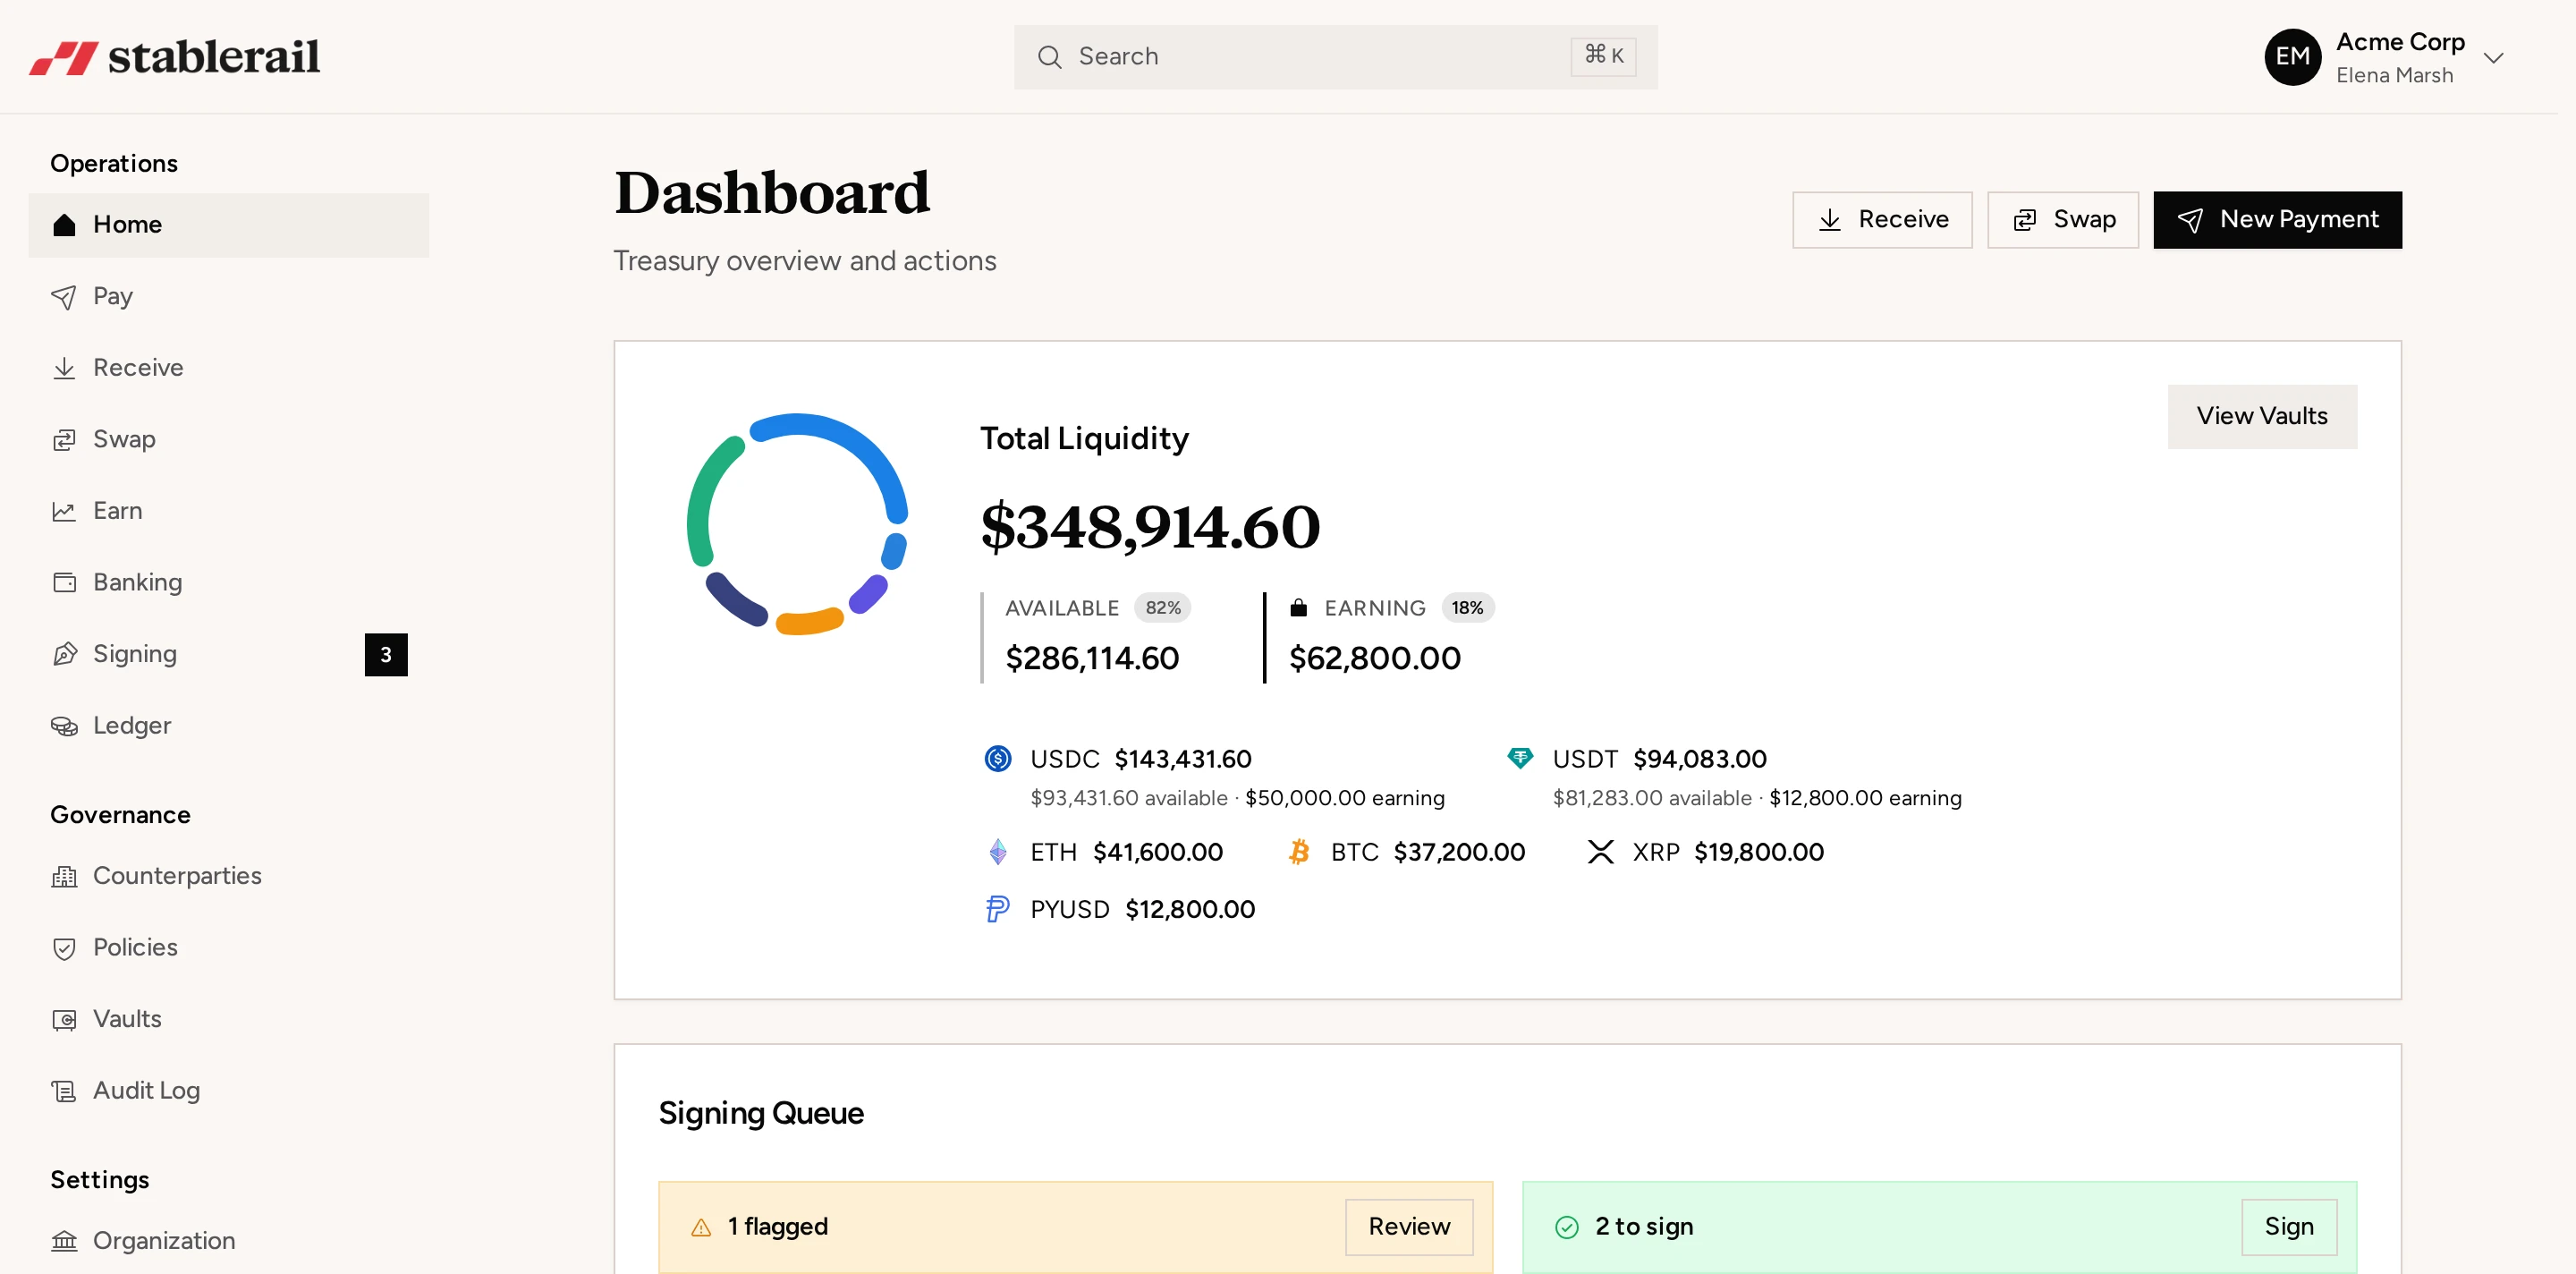
A company first holds USDC or USDT in its corporate treasury. With Stablerail, treasury funds can be held in self-custodial MPC vaults, where multiple approved signers can be required for sensitive transfers. The company can then allocate part of that treasury to its card programme.
The basic sequence is:
- Fund the treasury: Deposit USDC or USDT, or use a fiat on-ramp to convert EUR, USD or GBP into stablecoins.
- Allocate a card budget: Move an approved amount from the main treasury balance to the card programme or designated spending balance.
- Issue cards: Create virtual cards for online purchases or physical cards for employees who need point-of-sale access.
- Apply controls: Set employee limits, card-level limits and merchant category restrictions.
- Make purchases: The card network authorizes eligible transactions, typically within seconds.
- Settle and reconcile: Match the final card transaction, conversion record, receipt and accounting category.
This separation between the main vault and the spending allocation helps avoid exposing the full treasury balance to ordinary card activity. Teams considering this setup can review Stablerail’s corporate card capabilities.
What happens to USDC or USDT at purchase
Merchants generally receive their normal card settlement currency, not stablecoins. A purchase therefore involves conversion from the treasury asset into the relevant fiat or card settlement currency.
The exact conversion point depends on the card setup. Conversion may happen when the card balance is funded, when a transaction is authorized or when it is settled. Finance teams should confirm this because card authorization and final settlement are separate events. An authorization usually appears within seconds, while final settlement can take one to three business days and may differ from the authorized amount because of tips, deposits or currency conversion.
Before adopting a card programme, ask for a clear breakdown of:
- The exchange rate source used for USDC or USDT conversion.
- Any conversion spread or card funding fee.
- Foreign exchange charges when the purchase currency differs from the card currency.
- Card issuance, replacement or monthly fees.
- Cash withdrawal, refund and chargeback treatment.
Stablecoins such as USDC are designed to track the US dollar, but that does not mean every conversion is completed at exactly one dollar. Liquidity, network fees, provider spreads and market conditions can affect the final treasury cost.
Corporate card controls
Effective spend controls should prevent obvious policy breaches before they become reconciliation problems. Stablerail supports virtual and physical corporate cards with limits and merchant category code controls.
| Control | How finance teams use it | Important limitation |
|---|---|---|
| Per-transaction limit | Caps the value of an individual purchase | Large expenses may need a temporary increase |
| Daily or monthly limit | Sets a total spending budget for each employee or card | Pending transactions may affect available capacity |
| Merchant category control | Allows or blocks categories such as travel, software or entertainment | Merchant category codes are assigned by acquirers and are not always precise |
| Virtual card | Separates vendors, subscriptions or projects using distinct card numbers | Some merchants do not accept virtual cards |
| Card freeze | Stops new authorizations if a card is lost or no longer needed | Previously authorized transactions may still settle |
Limits should reflect the employee’s role. For example, an engineer may need a small monthly software budget, while a travel manager may need a larger limit restricted to airlines and hotels. These are policy decisions rather than universal thresholds.
Approvals without slowing every purchase
Card spending works best when routine purchases do not require finance to approve each transaction manually. The approval should happen when the budget and card rules are created.
A practical model is to approve the cardholder, spending purpose, monthly limit and permitted merchant categories in advance. Purchases that remain inside those rules can proceed normally. Exceptions—such as a one-off equipment purchase above the employee’s limit—can require an approval before finance raises the limit or creates a dedicated virtual card.
Higher-risk treasury actions should remain separate. Funding the card programme or transferring a large amount from the main vault can use quorum signing, meaning a defined number of authorized people must approve the movement. This keeps routine card use convenient while protecting the underlying stablecoin balance.
Receipt capture and expense categorization
The card transaction is only one part of the accounting record. Finance also needs the business purpose, receipt or invoice, employee identity, tax treatment and general ledger category.
A useful expense tracking workflow is:
- Notify the cardholder when a transaction is authorized or settled.
- Request a receipt and short business-purpose note.
- Match the receipt to the card transaction using amount, date and merchant.
- Assign a category, cost centre, legal entity and project where relevant.
- Flag missing receipts, duplicate charges or purchases outside policy.
- Retain the transaction and approval history as audit evidence.
Receipt collection may be handled in the card or expense system used by the company. Before implementation, confirm how card transaction data and supporting documents can be exported or linked to the general ledger. A common internal policy is to require receipts within 24 to 72 hours, although the right deadline depends on the company’s operating model.
Reconciling stablecoin-funded card spend
Reconciliation needs to connect two records: the treasury funding movement and the individual card transactions funded by it. Treating only the card statement as the source of truth can leave unexplained differences in the stablecoin ledger.
At month-end, finance should reconcile:
- The opening USDC or USDT balance.
- Amounts allocated to the card programme.
- Stablecoin-to-fiat conversion values and fees.
- Authorized, settled, reversed and refunded card transactions.
- Outstanding card balances and pending transactions.
- Receipts, accounting categories and tax documentation.
- The closing treasury and card programme balances.
Refunds deserve particular attention. A merchant refund may arrive days after the original purchase and may not reverse the exact stablecoin amount originally spent because conversion rates or fees can differ. Record the refund as its own event rather than deleting the original expense.
A practical setup checklist
Before issuing cards broadly, finance teams should complete KYB onboarding and confirm that their jurisdiction and industry are eligible. They should then start with a limited group of cardholders and validate the full process from treasury funding through accounting close.
- Choose the stablecoin and card settlement currencies.
- Document conversion pricing and card fees.
- Define employee, transaction and monthly limits.
- Configure permitted and blocked merchant categories.
- Set rules for temporary limit increases and exceptions.
- Decide where receipts and expense categories will be maintained.
- Test purchases, reversals, refunds and foreign-currency transactions.
- Confirm that the audit log and evidence packs meet finance requirements.
Stablecoin spend management is most useful when it turns treasury assets into controlled operating spend without creating a separate manual ledger. Corporate cards provide the payment method; limits, merchant controls, receipt capture and reconciliation make the process workable for finance.
Finance writers covering stablecoin treasury, payments, compliance, and risk controls.
More about the Stablerail team- Stablecoin treasury managementApprovals, limits, yield and reporting on one balance.
- Stablecoin payoutsBatch contractor and vendor payments with screening.
- USDT vs USDCWhich stablecoin your company should settle in.
- Stablecoin finance glossaryMPC, off-ramp, travel rule and the rest, in plain English.
- Product updatesEverything we ship, month by month.