Agent-Led Treasury: Where AI Can Act and Where Finance Teams Should Stay in Control
Learn how to divide treasury work between AI agents and finance teams, with practical controls for payments, stablecoins, reconciliation, routing and approvals.
Agent-led treasury should let AI monitor balances, reconcile activity, compare payment routes and prepare transactions, but not independently control corporate funds. Humans should approve material transfers, new beneficiaries, policy changes and exceptions. The safest model separates recommendation, approval and signing, applies sanctions and address screening before execution, and preserves evidence showing what the agent proposed, what reviewers changed and who authorised the final transaction.

Agent-led treasury should automate observation, analysis and transaction preparation while keeping people accountable for material movement of corporate funds. An agent can monitor fiat and stablecoin balances, identify funding needs, match payments and draft transfers. It should not receive unrestricted authority to add recipients, override warnings or release funds. The effective control boundary is between preparing an action and approving and signing it.
What agent-led treasury means
Agent-led treasury is an operating model in which software agents continuously review treasury data, identify required actions and prepare work for the finance team. The agent may monitor EUR, USD, USDC and USDT balances, recommend a conversion, assemble a contractor payout batch or match an incoming payment to an invoice.
This is different from giving a general-purpose AI access to bank and wallet credentials. A controlled agent operates through limited permissions, defined data sources and an approval workflow. It explains why an action is needed, prepares the instruction and sends it to authorised reviewers. The payment platform, bank or wallet then applies its own approval and signing controls before releasing funds.
Deterministic rules should govern hard boundaries such as transaction limits, permitted assets, approved recipients and required signing quorum. AI is better used for interpretation: summarising a cash position, finding likely invoice matches or explaining why one payment route may be preferable. A model’s recommendation must never override an enforced control.
How an agent-led workflow operates
- Observe: Read balances, pending transactions, forecasts, payment files, exchange rates and wallet activity from approved systems.
- Detect: Identify a projected cash shortfall, unmatched receipt, duplicate payment, overdue invoice or funding requirement.
- Propose: Recommend an action with the amount, asset, destination, route, expected costs and timing assumptions.
- Prepare: Create a draft transfer, conversion or payout batch without releasing funds.
- Approve and sign: Route the draft to authorised people and enforce the required signing quorum independently of the agent.
- Verify and record: Confirm the result, reconcile the completed transaction and preserve evidence for accounting and audit review.
For example, an agent could detect that a USD operating account is projected to fall below its approved buffer. It could propose converting company-held USDC to USD, identify the balance and forecast entries behind the recommendation, and prepare the conversion. A treasury manager would verify the assumptions, while the treasury platform would require the applicable approvals before execution.
Which treasury activities should be automated?
Good automation candidates are frequent, rules-based and easy to review. Human involvement should increase with the value, novelty, irreversibility and legal or operational impact of the decision.
| Activity | Appropriate agent role | Human control | Stop condition |
|---|---|---|---|
| Balance monitoring | Monitor accounts and wallets; calculate available liquidity | Approve thresholds and forecasting method | Missing, stale or conflicting balance data |
| Cash-position reporting | Aggregate fiat and stablecoin balances | Confirm ownership, restrictions and accounting treatment | Unverified account or asset classification |
| Routine reconciliation | Suggest matches using amount, reference, sender and timing | Resolve ambiguous or conflicting matches | More than one plausible match or unexpected sender |
| Payment batches | Validate files, detect duplicates and prepare drafts | Approve the batch and review new recipients | Changed bank details, wallet address or duplicate reference |
| Fiat or stablecoin conversion | Compare routes and prepare an instruction | Approve asset, amount, price and destination | Unavailable quote, excessive variance or unsupported route |
| Emergency funding | Alert the team and present alternatives | Make the decision and satisfy signing quorum | Insufficient evidence or inability to complete required checks |
| Policy or access changes | Identify a possible need and draft a request | Approve, implement and document every change | Agent attempts to change its own permissions |
Reconciliation illustrates the difference between assistance and uncontrolled autonomy. A USDC receipt may be matched automatically when the amount, expected wallet, reference and timing all agree. If several invoices have the same value or funds arrive from an unfamiliar address, the agent should create an exception instead of forcing a match.
How agents should compare payment routes
A treasury agent can compare bank rails, cross-border transfers and stablecoin networks, but its recommendation must expose the relevant inputs. The reviewer needs to understand whether the choice is based on a cut-off, recipient capability, quoted cost, settlement requirement or available liquidity.
| Route | Agent should evaluate | Required control |
|---|---|---|
| Domestic bank transfer | Bank cut-off, value date, return risk and beneficiary details | Verified beneficiary and approved payment file |
| Cross-border bank transfer | Currency path, intermediary deductions, compliance review and arrival estimate | Approved destination, purpose and conversion terms |
| Stablecoin transfer | Asset, blockchain network, wallet compatibility, network fee and available balance | Address screening, network confirmation and signing quorum |
| Fiat-to-stablecoin conversion | Quoted conversion terms, funding source and destination wallet | Approved asset, company-owned destination and recorded quote |
| Stablecoin-to-fiat conversion | Off-ramp availability, destination account and expected proceeds | Company-owned bank account and approval before execution |
Address and network validation are separate controls. An agent must not assume that two addresses are interchangeable across blockchains, even when their character formats appear similar. It should also avoid relying on a cached quote or old screening result when preparing a new transfer.
Decisions that should remain under human control
Human approval is appropriate whenever an action changes the company’s exposure or weakens an existing safeguard. At a minimum, finance teams should retain control over:
- Adding or changing a bank account, beneficiary or wallet address.
- Making a first payment to a recipient.
- Sending a payment above the relevant approval tier.
- Using a new asset, blockchain network, payment rail or jurisdiction.
- Executing a material conversion between fiat, USDC and USDT.
- Overriding a sanctions, address-screening or recipient-verification warning.
- Changing user access, transaction limits, approval rules or signing quorum.
- Committing treasury funds to a product with liquidity, counterparty or loss risk.
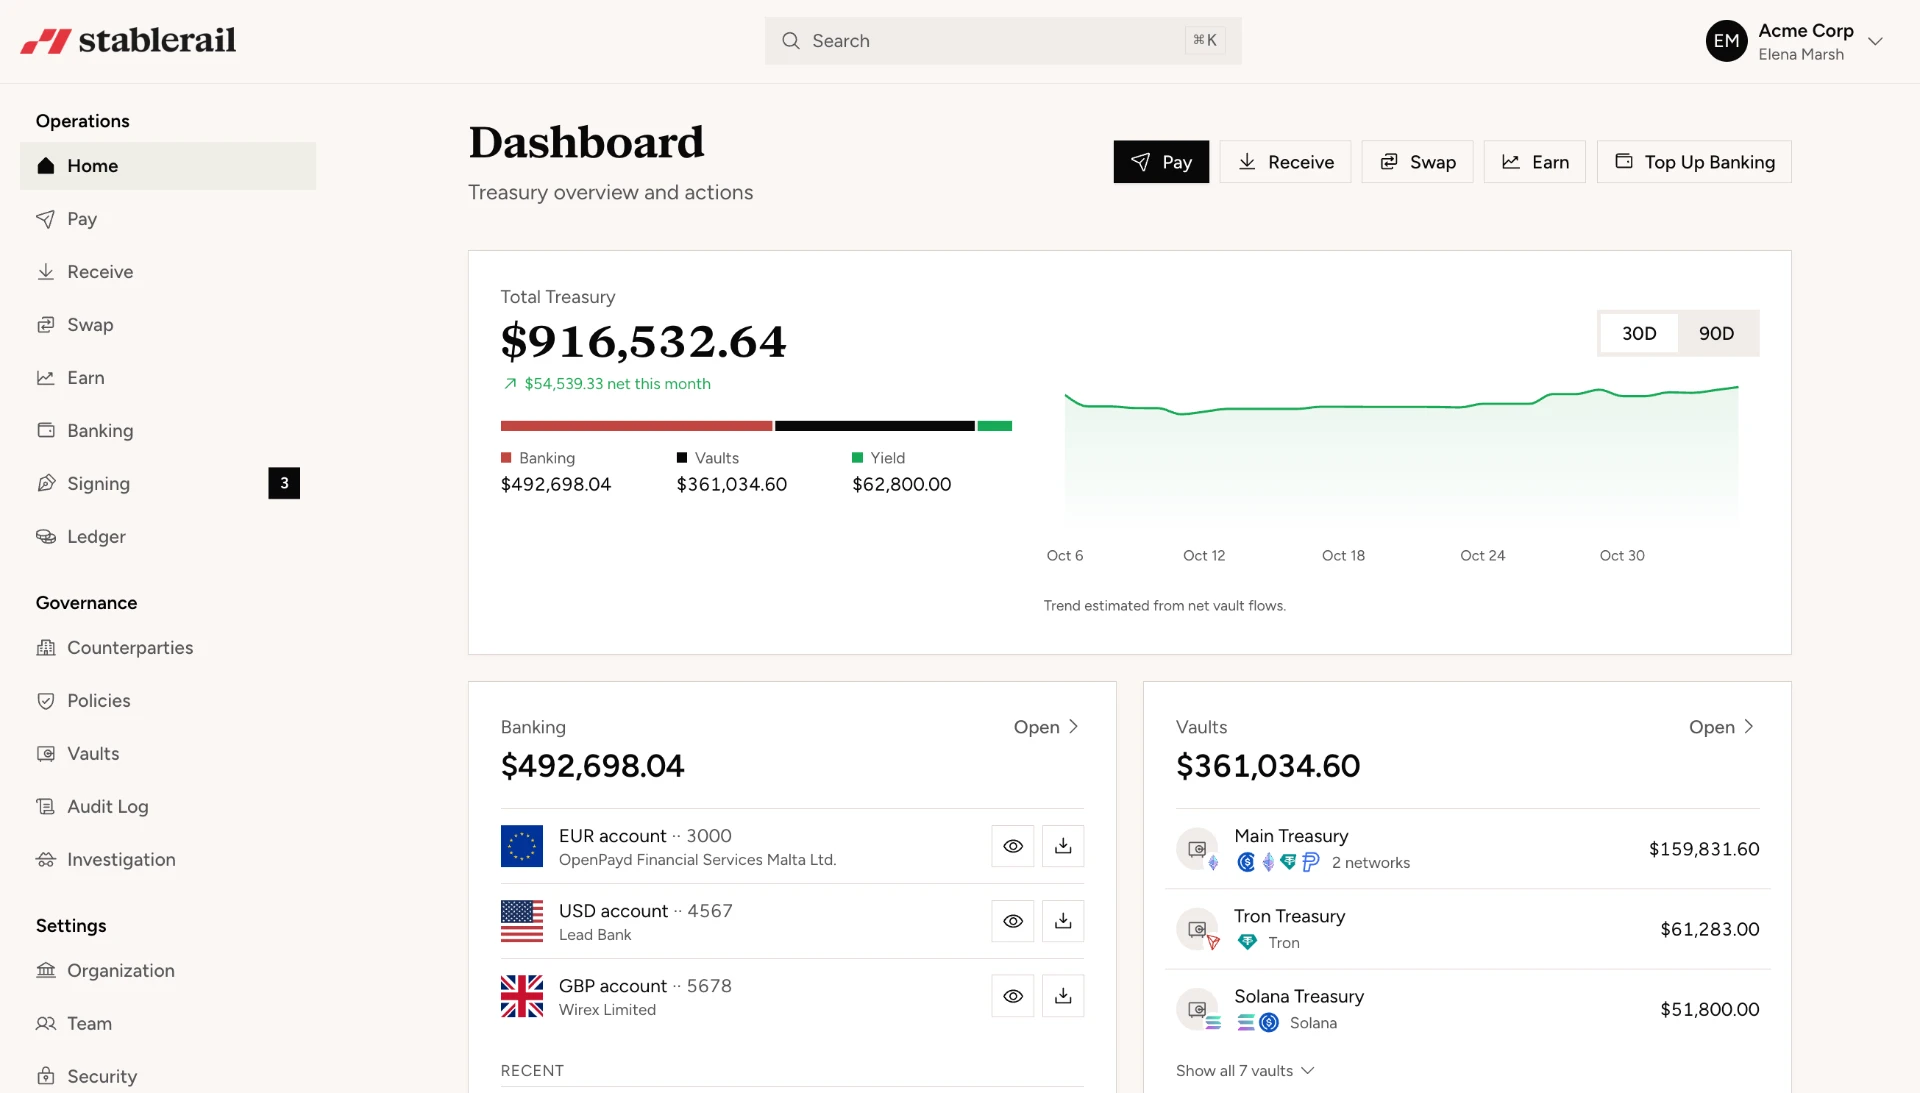
Segregation of duties should exist outside the agent. The person who creates or changes a recipient should not be able to approve the first payment alone. Likewise, an agent may prepare a transaction payload, but the treasury system should independently enforce approvals and signatures. Stablerail, for example, supports approvals and signing quorum, sanctions and address screening before send, and exportable audit evidence for company-owned USDC and USDT treasury operations.
Set boundaries before connecting an agent
Instructions such as “keep enough cash for payroll” are too vague to function as controls. Finance teams should translate treasury policy into measurable rules and define what happens when required information is missing.
- Balance rules: Specify the operating buffer, covered entities, currencies, forecast horizon and approved source data.
- Transaction rules: Set preparation and approval tiers by amount, asset, entity and transaction type.
- Recipient rules: Require verified details for existing recipients and separate review for additions or changes.
- Asset rules: Define whether the company may hold USDC, USDT or both and identify permitted networks and wallets.
- Timing rules: Account for bank cut-offs, non-business days, payroll deadlines and blockchain confirmation requirements.
- Exception rules: Stop when pricing, screening, beneficiary data, balances or approvals are unavailable.
The same principle applies to corporate cards. An agent can flag unusual spending, prepare a funding recommendation or suggest a temporary limit adjustment. Permanent changes to card limits, authorised users or spending controls should require an authorised administrator. Where cards, global payouts and fiat conversion draw from the same corporate treasury, the consolidated cash view should distinguish available funds from pending or reserved balances.
Make every recommendation reviewable
An approver needs an evidence package, not a one-line request. Every proposed movement should show:
- The source and destination account or wallet.
- The legal entity, amount, asset and blockchain network where applicable.
- The rule, forecast or obligation that triggered the proposal.
- The recipient’s verification, allowlist and screening status.
- The quote, fees, settlement assumptions and relevant cut-off.
- The invoice, payroll file or other supporting record.
- Who created, edited, approved, signed and released the instruction.
The audit trail should retain the original recommendation and all subsequent changes. If a reviewer changes the amount, route or destination, the system should record the old and new values rather than replacing the proposal. It should also capture failed attempts, rejected approvals and the transaction identifier produced after execution.
A practical implementation checklist
- Inventory every data source, payment rail, wallet and credential the agent could reach.
- Begin with read-only balance monitoring and exception alerts.
- Test recommendations against historical transactions and known edge cases.
- Add draft preparation without payment-release authority.
- Require human approval for every transaction during the initial operating period.
- Measure false matches, duplicate alerts, missing evidence and reviewer overrides.
- Review permissions, thresholds and signing participants on a defined schedule.
- Expand automation only when the control owner accepts the observed exception pattern.
Agent-led treasury is strongest when automation reduces manual collection and preparation without obscuring accountability. Agents can make treasury teams faster, but banks, wallets and treasury platforms must still enforce who can approve and sign. The target is controlled execution with better evidence, not autonomy for its own sake.
Frequently asked questions
What is agent-led treasury?
Agent-led treasury uses software agents to monitor balances, analyse transactions and prepare treasury actions. The finance team remains accountable for policy, exceptions and approval of material fund movements.
Should an AI treasury agent be allowed to send payments?
An agent may prepare a payment, but unrestricted signing or release authority creates unnecessary risk. The payment system should independently enforce approval tiers, recipient controls and signing quorum before corporate funds move.
Which treasury tasks are safest to automate with AI?
Balance monitoring, cash reporting, draft preparation and high-confidence reconciliation are strong starting points. New beneficiaries, policy changes, unusual transactions and material transfers should remain subject to explicit human review.
How should a company control an AI agent using stablecoins?
Limit the agent to approved company wallets, assets and networks, and require sanctions and address screening before send. Keep signing credentials outside the agent, enforce quorum approval, and record the proposal, reviewer changes and final transaction identifier.
What evidence should an AI-generated payment request include?
It should show the source, destination, amount, asset, purpose, supporting document, screening result, quoted costs and settlement assumptions. The audit record should also identify who prepared, changed, approved, signed and released the transaction.
Finance writers covering stablecoin treasury, payments, compliance, and risk controls.
More about the Stablerail team- Stablecoin treasury managementApprovals, limits, yield and reporting on one balance.
- Stablecoin payoutsBatch contractor and vendor payments with screening.
- USDT vs USDCWhich stablecoin your company should settle in.
- Stablecoin finance glossaryMPC, off-ramp, travel rule and the rest, in plain English.
- Product updatesEverything we ship, month by month.