What a Crypto Regulation Tool Can—and Cannot—Do for Your Business
Crypto regulation tools can monitor rules, verify businesses, screen wallets and preserve evidence. Learn where automation helps, where judgment remains essential and how to evaluate the options.
A crypto regulation tool can monitor rule changes, verify business identities, screen blockchain addresses, flag unusual transactions and preserve evidence for audits. It cannot determine every legal obligation, guarantee that a counterparty is legitimate or prove that a transfer is lawful. Finance teams should use these tools to apply documented policies consistently, route exceptions for review and record who approved each decision.

A crypto regulation tool can automate research, verification, screening, monitoring and evidence collection, but it cannot replace legal interpretation or accountable decision-making. For a finance team managing USDC or USDT, the important questions are what the tool checks, when it checks it, how exceptions are handled and whether the resulting evidence can be retrieved later.
The term covers several distinct product categories. A regulatory intelligence platform may track new rules but perform no blockchain analysis. A wallet screening service may identify sanctions exposure but know nothing about a counterparty’s corporate ownership. Before comparing vendors, define the decision that each tool must support.
What the main types of crypto regulation tools do
| Tool category | Primary input | Useful output | What it cannot establish |
|---|---|---|---|
| Regulatory intelligence | Jurisdictions, activities, asset types and official publications | Rule updates, source documents, summaries and alerts | Whether a particular rule legally applies to your structure or activity |
| Know Your Business | Company identifiers, registry records, ownership details and documents | Verification status, ownership structure, screening results and risk flags | That every submitted fact is current, complete or authentic |
| Sanctions and wallet screening | Names, entities and blockchain addresses | Potential matches, attribution labels, exposure paths and risk categories | That an address is safe, unlawful or controlled by the stated counterparty |
| Transaction monitoring | Transfers, counterparties, amounts, networks and historical behavior | Alerts for activity that matches defined scenarios | That an alert proves wrongdoing or that unflagged activity is legitimate |
| Reporting | Transactions, cases, reviews and dispositions | Internal reports, management information and filing support | Which reports must be filed or which format a regulator will accept |
| Evidence management | Approvals, screening results, notes and supporting records | Searchable histories and exportable evidence packs | That the underlying policy or decision was correct |
Regulatory intelligence monitors change, not legal meaning
Regulatory monitoring tools collect updates from regulators, legislatures and other official sources. Useful filters for a corporate stablecoin treasury may cover custody, payments, sanctions, money transmission, licensing, tax reporting and consumer protection. A useful alert identifies the affected jurisdiction and topic, links to the original publication and records its publication or effective date.
Automated summaries help teams triage a large volume of material, but they should not become the sole legal record. Reviewers need access to the source text and any subsequent guidance, correction or implementation timetable.
The distinction between using stablecoins for a company’s own funds and providing services to customers can be legally significant. A rule directed at a payment service provider or custodian may not apply in the same way to an operating company paying its own vendors. The tool can identify the change; qualified counsel must determine its application to the business, entities and transaction flow.
KYB verifies a business within the available evidence
Know Your Business checks commonly begin with a legal name, registration number, registered address and registry extract. Depending on the risk and jurisdiction, the review may also collect directors, authorized signatories, ultimate beneficial owners, an ownership chart, business activity, expected transaction profile and source-of-funds evidence.
KYB software can retrieve registry information, compare names against sanctions or politically exposed person data, identify missing documents and route ambiguous cases for review. It can also prompt a refresh after documents expire or known company details change.
Its limits come from the underlying information. Registry coverage and update frequency vary, ownership may pass through several entities, and a newly formed business may have little operating history. A successful database match does not prove that the person communicating with your finance team controls the company or the destination wallet. Payment instructions still require independent verification and appropriate approval controls.
Wallet screening and transaction monitoring answer different questions
Wallet screening assesses a specific address
Wallet screening evaluates a blockchain address before or during a transfer. Depending on the provider and network, it may identify direct or indirect exposure to sanctioned addresses, stolen funds, scams, ransomware, mixers or other defined categories.
The result requires context. Direct receipt from an identified address is different from a small indirect exposure several transfers removed. Attribution labels, clustering methods and risk scores can also differ between analytics providers. A treasury policy should therefore specify which findings block a payment, which require investigation and who may authorize an exception.
Screen the actual destination address on the actual network, not merely the counterparty name. Where an address is reused, define when it must be rescreened because exposure and attribution can change after initial approval.
Transaction monitoring looks for patterns
Transaction monitoring evaluates behavior across transfers. Scenarios might identify a sudden increase in volume, repeated payments just below an internal approval threshold, rapid movement through several addresses, or use of a new destination network. These are indicators for review, not conclusions about intent.
A useful alert should show the scenario that triggered, the relevant transactions and counterparties, the reviewer’s notes, supporting material and final disposition. Measuring success by alert volume creates noise. Finance and compliance teams should instead assess whether alerts identify relevant behavior and can be resolved consistently.
Evidence is part of the control, not an afterthought
A bank, auditor, regulator or internal reviewer may ask more than whether screening occurred. They may need to know which address was checked, which data was returned at that time, who reviewed an exception and who approved the transfer.
A complete payment evidence pack should preserve:
- Counterparty identity and KYB records relevant to the decision.
- The destination address, blockchain network, asset and amount.
- Sanctions or wallet screening results captured before execution.
- Approval records, signing quorum and any exception authorization.
- The transaction identifier and execution timestamp.
- Alert notes, attachments, escalation history and final disposition.
- Related fiat conversion or bank references where applicable.
Exports should remain understandable without access to the original system. Confirm that timestamps use a consistent time zone, records identify their source, and retention settings align with legal, accounting and internal requirements. Also determine whether historical results remain available after a vendor changes its risk model or attribution.
How to select and test a crypto regulation tool
Begin with a real workflow rather than a generic feature list. Map a payment from counterparty onboarding and address collection through approval, signing, execution, reconciliation and evidence export. Then identify where the payment must stop if a check fails or cannot be completed.
- Confirm coverage. Verify the exact jurisdictions, stablecoins, blockchain networks and legal entities the tool supports.
- Inspect data sources. Ask which official lists, corporate registries and blockchain data sources are used, and how updates are reflected.
- Demand explainability. Reviewers need the reason for an alert, relevant exposure or match details, and the data timestamp—not only a numerical score.
- Define operational outcomes. Decide whether each result blocks, queues or permits a payment and who can release an exception.
- Test permissions and evidence. Check whether finance, compliance and auditors can receive appropriately limited access and complete exports.
- Plan for outages. Document whether delayed or unavailable screening causes a hold, retry or manual escalation. Avoid silently treating a missing result as a pass.
Test shortlisted tools with cases your team understands: clean counterparties, common name matches, previously investigated alerts and addresses with different kinds of exposure. Compare the relevance of results, time required to resolve exceptions and completeness of the exported record. A fast response is not useful if the reviewer cannot understand or defend it.
What a crypto regulation tool cannot do
No tool can guarantee that a transfer is lawful, that a counterparty is honest or that an unflagged wallet is safe. Name screening can create false matches. Blockchain attribution may be incomplete and can change as new evidence emerges. A legitimate business may trigger an alert because of indirect historical exposure, while a fraudulent counterparty may use a newly created address with no observable risk history.
The software also cannot decide whether your company needs a licence, whether a stablecoin activity falls within a regulated category, when a report must be filed or how conflicting requirements apply across jurisdictions. Those decisions require analysis of the company’s activities, contractual role, entities and locations.
The tool supplies signals and evidence. The company remains responsible for the policy, the exception decision and the transfer.
Putting the controls into treasury operations
Compliance checks are strongest when they sit inside the payment workflow rather than in a separate spreadsheet or after-the-fact review. For every payment path, assign an owner for counterparty verification, destination validation, alert review, approval, execution and reconciliation. Separate duties where practical, and require exceptions to be documented before funds move.
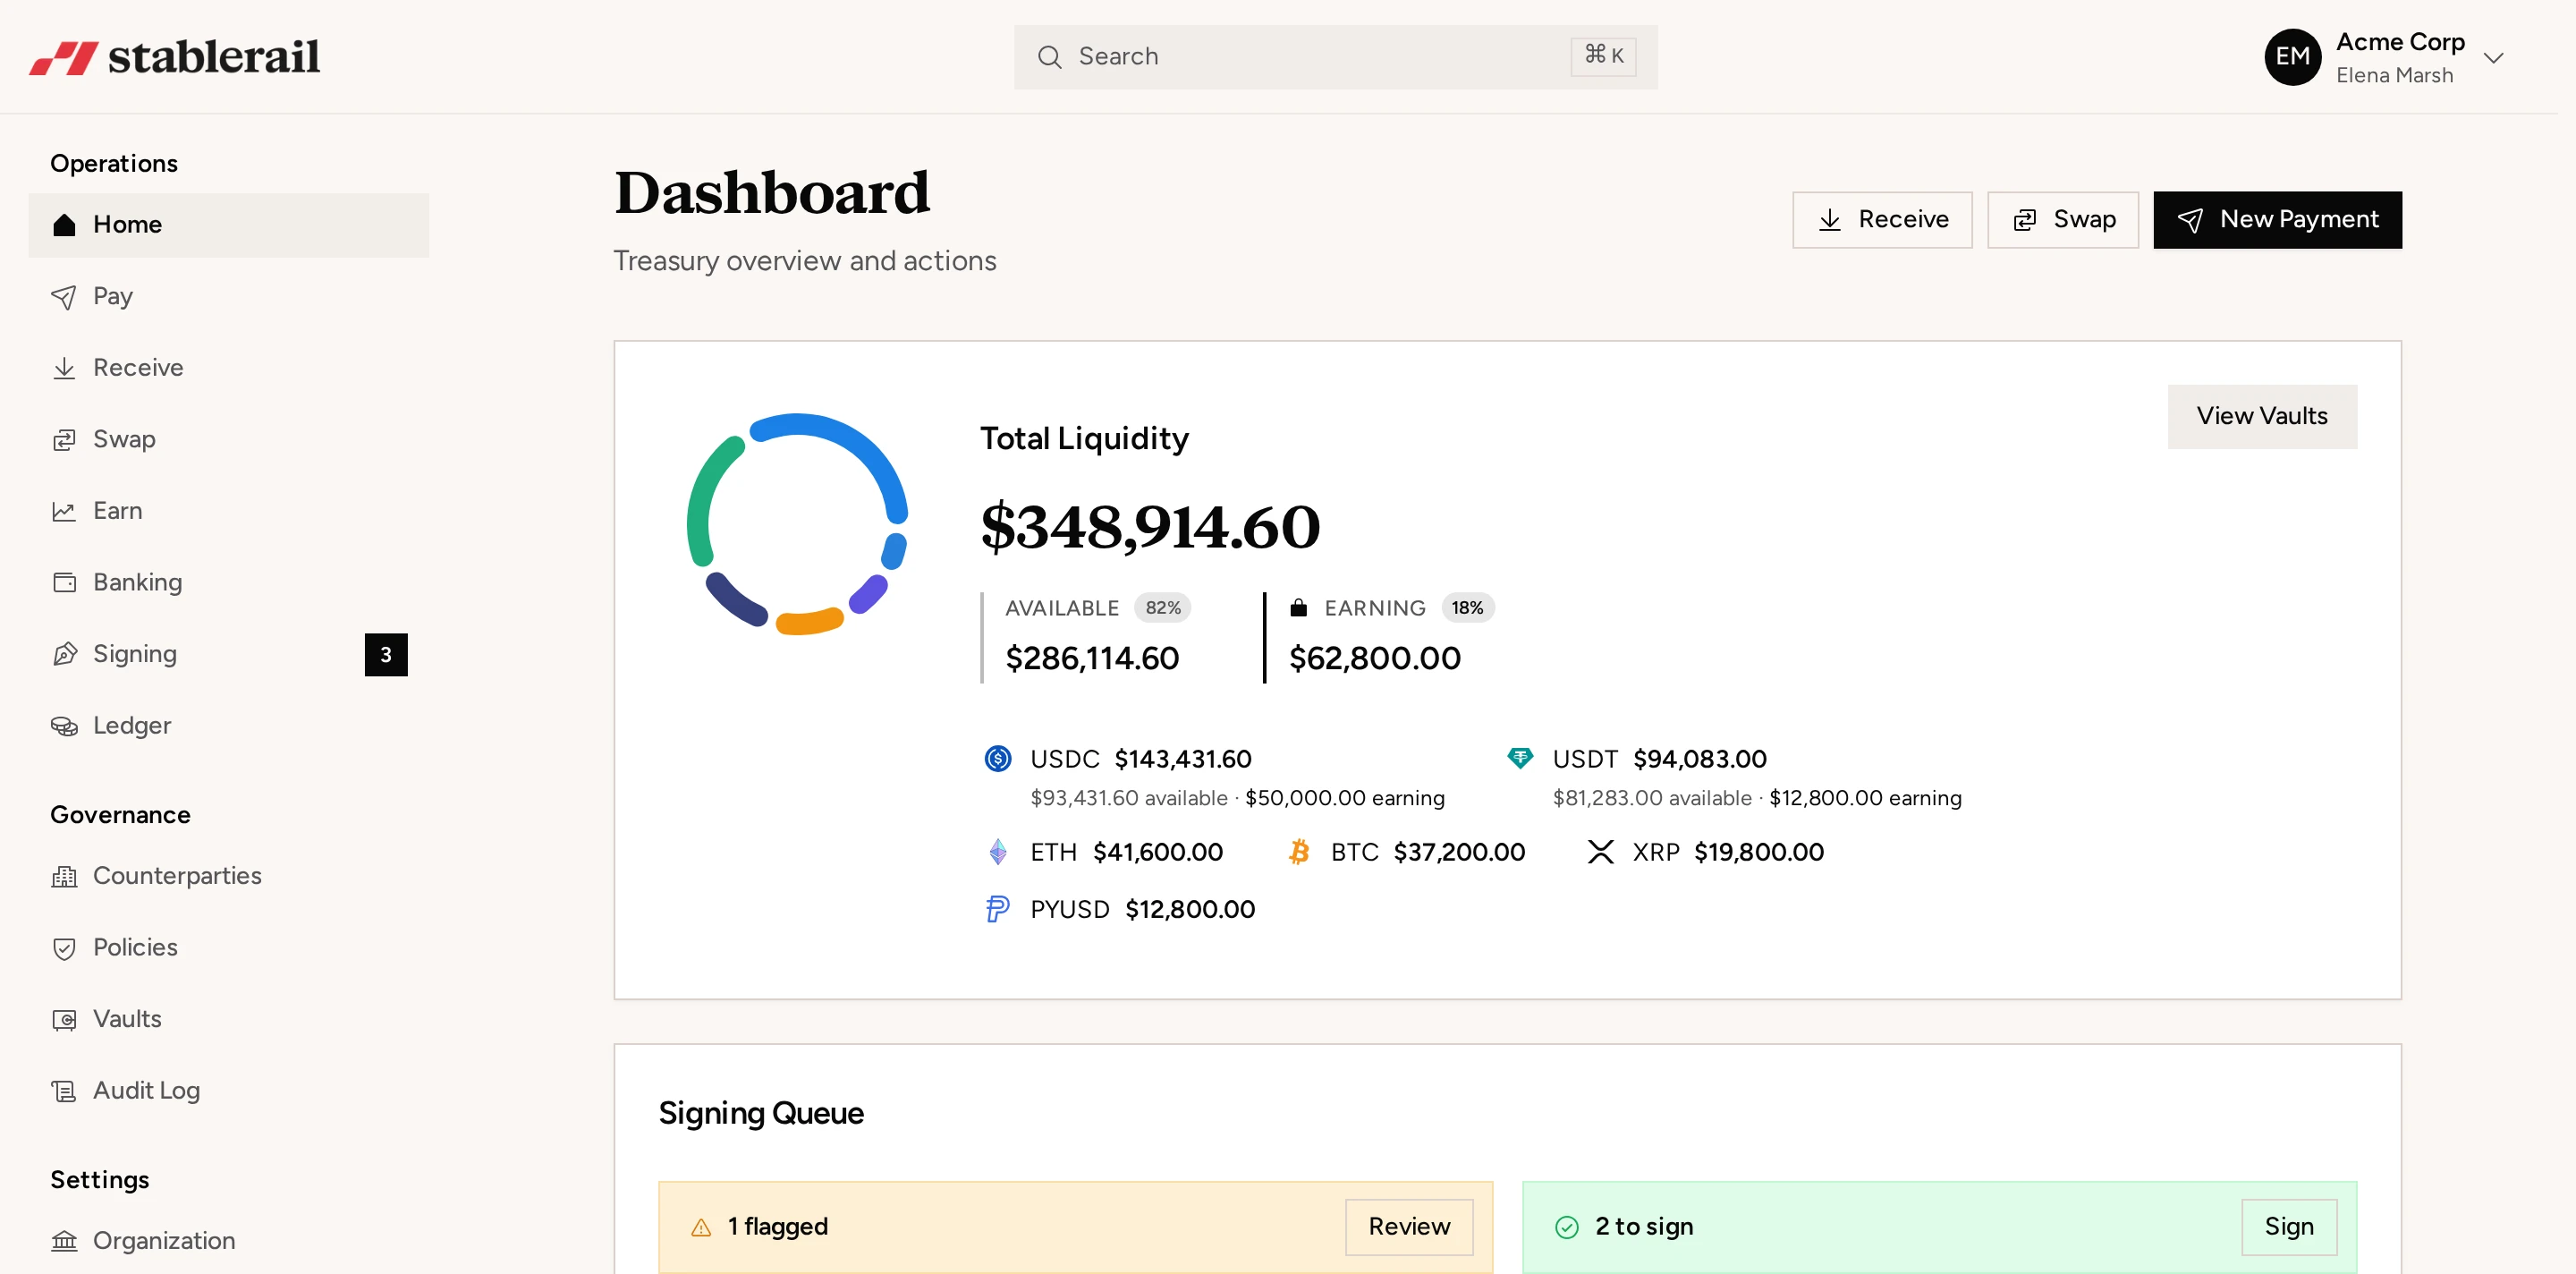
Stablerail places sanctions and address screening alongside approvals and signing quorum for companies managing their own USDC or USDT. It also supports corporate cards, global payouts, fiat conversion and exportable audit evidence. Regardless of platform, the operating principle is the same: validate each destination before sending, stop unresolved exceptions and retain enough evidence to reconstruct the decision.
A crypto regulation tool is therefore best treated as control infrastructure, not an assurance label. Its value comes from reliable data, clear escalation rules, accountable human review and records that show exactly how a finance team reached its decision.
Frequently asked questions
What does a crypto regulation tool do?
A crypto regulation tool may track regulatory changes, perform KYB, screen blockchain addresses, monitor transaction patterns or preserve compliance evidence. Because products cover different functions, finance teams should define the decision they need to support before selecting a tool.
Can a crypto compliance tool determine whether a stablecoin payment is legal?
No. A tool can identify sanctions matches, wallet exposure and activity that meets predefined alert rules, but it cannot provide a definitive legal conclusion. The company and its advisers must assess applicable laws, licensing questions and reporting duties.
What is the difference between wallet screening and transaction monitoring?
Wallet screening evaluates a specific blockchain address, usually before or during a transfer. Transaction monitoring looks across activity over time to identify patterns such as unusual volume, threshold avoidance or rapid movement between addresses.
Should a company screen a USDC or USDT address before every payment?
The screening frequency should follow the company’s documented risk policy, but screening before execution captures information available at the point of payment. Previously approved addresses may need to be screened again because sanctions designations, attribution and blockchain exposure can change.
What records should be kept for a stablecoin payment audit?
Keep the counterparty record, destination address, network, asset, amount, pre-transfer screening result, approvals, exception notes, transaction identifier and reconciliation evidence. Records should use consistent timestamps and remain understandable when exported from the original system.
Finance writers covering stablecoin treasury, payments, compliance, and risk controls.
More about the Stablerail team- Stablecoin treasury managementApprovals, limits, yield and reporting on one balance.
- Stablecoin payoutsBatch contractor and vendor payments with screening.
- USDT vs USDCWhich stablecoin your company should settle in.
- Stablecoin finance glossaryMPC, off-ramp, travel rule and the rest, in plain English.
- Product updatesEverything we ship, month by month.