SEPA and SEPA Instant for business accounts: how euro payments actually clear
Understand how SEPA Credit Transfer and SEPA Instant differ on speed, cut-offs, costs and IBAN requirements—and how euro balances connect with USDC and USDT at Stablerail.

A SEPA business account lets a company send and receive euro payments using an IBAN across the Single Euro Payments Area. But “SEPA” can refer to two different payment routes: standard SEPA Credit Transfer and SEPA Instant Credit Transfer.
The practical difference is not just speed. The routes have different operating hours, cut-off considerations and bank support. Finance teams also need to distinguish the payment’s clearing time from any later conversion between euros and USDC or USDT.
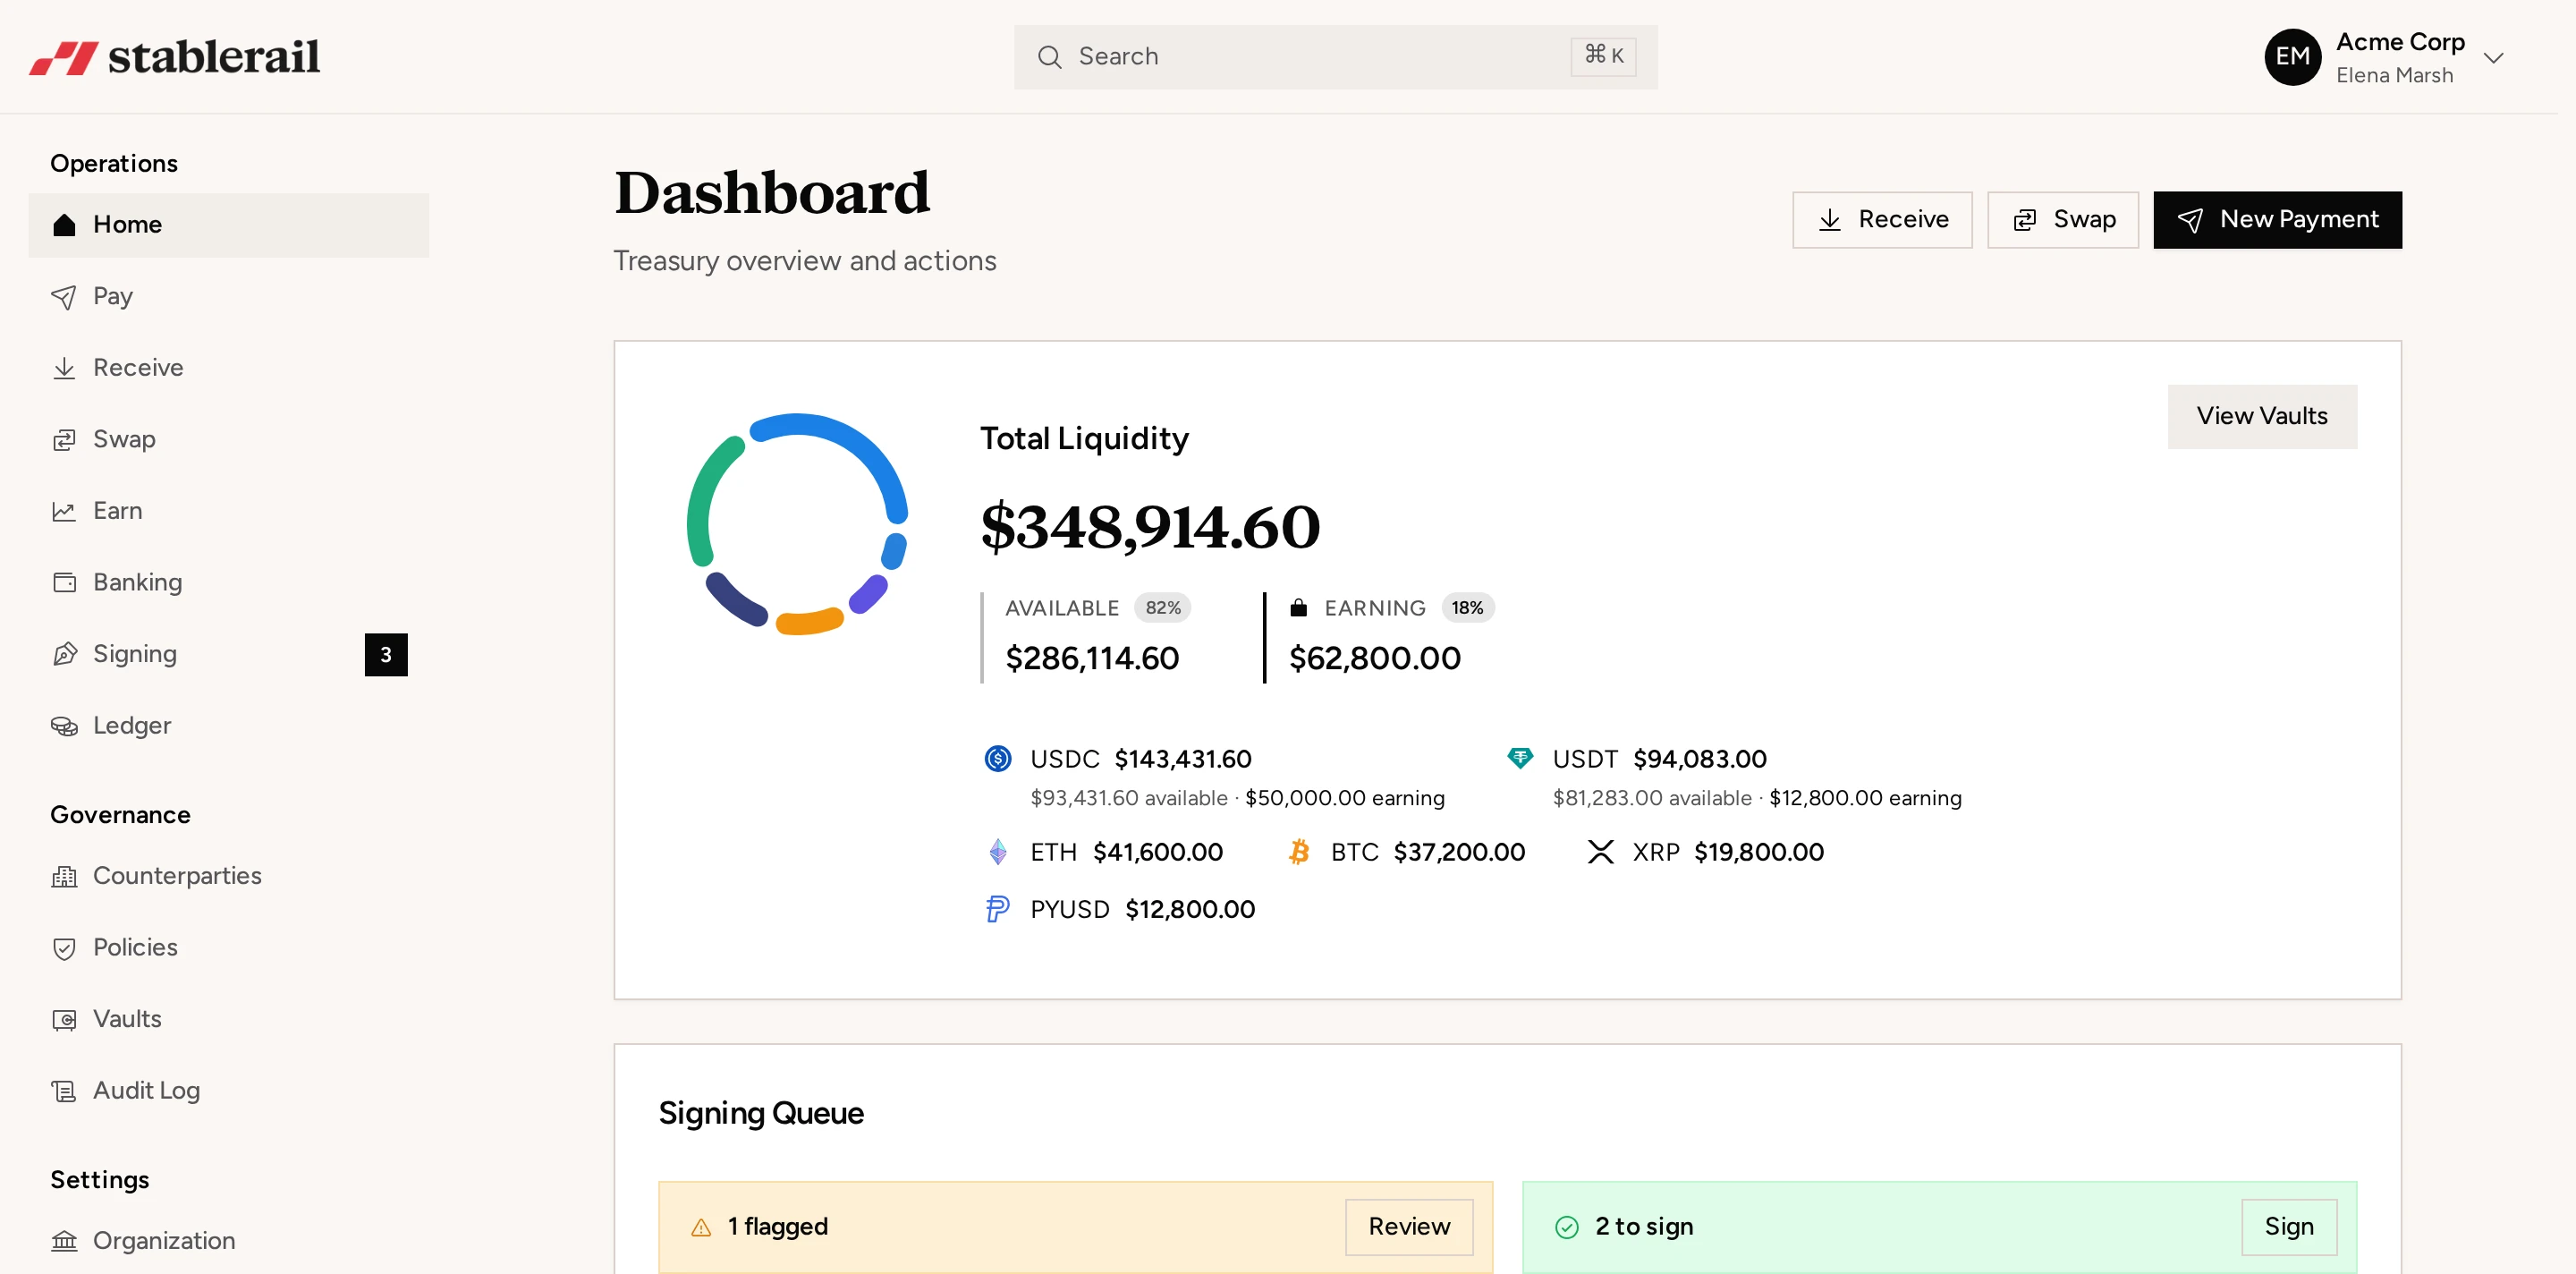
At Stablerail, an eligible business can hold a euro balance with euro payment details alongside its stablecoin treasury. This provides one operating flow for receiving EUR, converting between fiat and supported stablecoins, and making fiat or blockchain payouts.
SEPA Credit Transfer versus SEPA Instant
SEPA Credit Transfer, commonly shortened to SCT, is the standard route for euro bank transfers. SEPA Instant Credit Transfer, or SCT Inst, is the real-time version.
| Feature | SEPA Credit Transfer | SEPA Instant |
|---|---|---|
| Typical speed | Same day or next banking business day | Usually seconds |
| Scheme execution target | Up to one banking business day after the payment order is received | Within 10 seconds |
| Operating hours | Processed on banking business days | 24 hours a day, 365 days a year |
| Weekends and holidays | Usually wait until the next banking business day | Designed to process without waiting |
| Cut-offs | Provider-specific daily cut-offs apply | No traditional end-of-day cut-off, although maintenance and account controls may apply |
| Availability | Widely supported across SEPA | Both the sending and receiving providers must support instant payments |
| Transaction limits | Set by the payment provider and account agreement | Provider or account limits may apply even where the scheme supports larger amounts |
“Within 10 seconds” describes the SEPA Instant scheme target. It does not guarantee that every instruction will succeed. A payment can still be rejected because of an incorrect IBAN, insufficient funds, account limits, sanctions screening, provider downtime or an unsupported receiving institution.
How a standard SEPA payment clears
A standard SEPA payment moves through several stages:
- Instruction: The payer submits the beneficiary name, IBAN, amount and payment reference.
- Acceptance: The payer’s provider checks the available balance, payment details and applicable restrictions.
- Clearing: The payment is exchanged through a SEPA clearing mechanism.
- Settlement: The participating payment providers settle the amount between them.
- Credit: The beneficiary’s provider posts the funds to the receiving account.
If an instruction reaches the provider before its cut-off on a banking business day, it may arrive the same day, but the standard expectation should be no later than the next banking business day. A payment submitted after Friday’s cut-off may not be treated as received until Monday, assuming Monday is not a bank holiday.
Cut-offs are not universal SEPA times. They depend on the provider, payment channel, currency conversion requirements and whether an instruction is submitted individually or as part of a batch. Finance teams should record the cut-off stated for their specific account rather than assume that all euro payments follow the same timetable.
How SEPA Instant clears
SEPA Instant runs continuously rather than in end-of-day banking cycles. The sending provider validates the instruction and sends it through an instant clearing system. The receiving provider confirms whether the beneficiary account can be credited, normally within seconds.
This makes SEPA Instant useful for urgent supplier payments, time-sensitive treasury funding and weekend transfers. It can also reduce the uncertainty between a payer marking an invoice as paid and the beneficiary seeing the money.
Businesses should still confirm the transaction status before treating a payment as complete. If an instant instruction times out or is rejected, do not immediately resend it without checking the account activity. Otherwise, a delayed status update could result in a duplicate payment.
What IBAN details are required?
An IBAN, or International Bank Account Number, identifies the destination account. Its length varies by country and it includes a country code, check digits and domestic account information.
For a typical euro payment, the payer needs:
- The beneficiary’s account name or registered business name
- The beneficiary IBAN
- The payment amount in EUR
- An invoice number or other reconciliation reference
- The payment purpose where requested
A BIC or SWIFT code is generally not required for routine SEPA payments when a valid IBAN is provided, although a provider may request additional information in specific cases.
Name-checking services may return an exact match, close match or no match between the entered beneficiary and the IBAN holder. This is especially relevant for companies using trading names, abbreviations or group treasury entities. A warning should be investigated rather than automatically overridden.
What does a SEPA payment cost?
SEPA does not mean that every transfer is free. Pricing is set by the account provider and may depend on the account plan, transaction volume, batch format and whether the payment is standard or instant.
For payment providers covered by EU instant-payment rules, the charge for sending or receiving a euro instant payment cannot be higher than the charge for the corresponding standard euro transfer. That does not necessarily make either route free. Different rules or pricing may also apply to providers outside the EU, including some institutions in the wider SEPA area.
When comparing costs, check more than the visible transfer fee:
- Monthly account or IBAN fees
- Inbound and outbound payment charges
- Batch payment fees
- Foreign-exchange costs if funds start or end in another currency
- Conversion pricing between EUR and USDC or USDT
- Blockchain network fees for a later stablecoin transfer
Stablerail publishes applicable corridor pricing rather than presenting the bank transfer, fiat-to-stablecoin conversion and blockchain payout as one indistinguishable cost. Finance teams should review the quoted conversion rate and fees before confirming a transaction.
How a euro IBAN works next to a stablecoin balance
For eligible Stablerail customers, euro payment details and a EUR balance can sit alongside self-custodial USDC and USDT vaults. The fiat account and stablecoin vault remain distinct balances, but they can be used in one treasury workflow.
A typical inbound flow is:
- Complete KYB and jurisdiction and industry eligibility checks.
- Activate the EUR balance and obtain the applicable euro IBAN or payment instructions.
- Receive EUR by standard SEPA or SEPA Instant, where supported.
- Reconcile the receipt using the sender, amount and payment reference.
- Keep the funds in EUR or request a conversion into USDC or USDT.
- Hold the stablecoins or send them over a supported blockchain network.
The reverse flow allows a business to convert supported stablecoins into EUR and then make a euro payment. Payment timing and conversion timing should be considered separately: receiving EUR by SEPA Instant does not by itself guarantee that every conversion or subsequent payout will complete within the same ten-second window.
For suppliers that prefer stablecoins, Stablerail supports stablecoin payouts across networks including Ethereum, Base, Arbitrum, Polygon, Tron, BNB Chain, Optimism and Solana. For fiat and digital-asset payment workflows, see the payout options.
Which route should your business use?
Use standard SEPA when the payment is planned, the beneficiary does not require immediate receipt, or the receiving provider cannot accept SEPA Instant. It is generally suitable for scheduled invoices, routine treasury transfers and non-urgent batches.
Use SEPA Instant when timing matters, including urgent supplier settlement, account funding outside normal banking hours or a payment needed before goods or services are released. Before sending a high-value instruction, confirm the provider’s transaction limit and verify the beneficiary details.
Whichever route you choose, record four items in the payment evidence: the submitted time, the provider’s acceptance status, the final transaction status and the beneficiary reference. Those details make it much easier to distinguish a payment that is still processing from one that has been rejected or completed.
Finance writers covering stablecoin treasury, payments, compliance, and risk controls.
More about the Stablerail team- Stablecoin treasury managementApprovals, limits, yield and reporting on one balance.
- Stablecoin payoutsBatch contractor and vendor payments with screening.
- USDT vs USDCWhich stablecoin your company should settle in.
- Stablecoin finance glossaryMPC, off-ramp, travel rule and the rest, in plain English.
- Product updatesEverything we ship, month by month.