Earning Yield on Idle Stablecoin Treasury: Sources, Risks and Liquidity Terms
A practical guide to earning yield on idle USDC or USDT, including return sources, withdrawal mechanics, risk reviews, allocation sizing and treasury controls.
USDC and USDT do not pay interest merely by remaining in a wallet. A company earns stablecoin yield by allocating tokens to an underlying security, lending market, borrower or trading strategy. Before allocating, finance teams should identify the legal claim, source of return, custody model, fees, withdrawal conditions and loss scenarios. Only funds not needed for operations or stress reserves should be exposed.

What stablecoin yield actually represents
Stablecoin yield is compensation for providing capital, accepting risk or giving up immediate access to funds. The token itself is not generating the return. Interest or trading income must come from an underlying borrower, security or strategy.
That distinction matters because two products quoting similar annual percentage yields may expose a company to entirely different risks. One might hold short-term US government securities through a fund structure. Another might lend stablecoins through smart contracts. A third might extend unsecured or partially secured credit to a trading firm.
A treasury review should therefore begin with a simple question: What economic activity produces the return, and what legal or technical claim does the company receive? If the provider cannot explain that mechanism in plain language, the quoted rate is not sufficient grounds for allocating corporate funds.
Four common sources of stablecoin yield
Short-term government securities
Some products convert stablecoins into exposure to Treasury bills, government money market funds or other short-duration instruments. Returns generally follow short-term US dollar interest rates after management, custody, conversion and operating fees.
The structure determines the company’s rights. It may own fund shares, hold a token representing an interest in a fund, or have only a contractual claim against a provider. Those arrangements can differ in eligibility, investor protection, insolvency treatment, redemption mechanics and tax consequences.
Government securities may have low underlying credit risk, but the product is not equivalent to stablecoins in an operating wallet or cash in an insured bank account. Redemptions can depend on business-day cutoffs, securities settlement, custodians and banking rails.
Onchain lending
Onchain markets allow companies to supply USDC, USDT or other assets to pools used by borrowers. Rates are usually variable and influenced by utilization. As more of a pool is borrowed, the rate may rise to attract additional supply and encourage repayment.
Withdrawals can settle quickly when the network is functioning and the pool contains enough unborrowed assets. However, an “on-demand” withdrawal is not necessarily guaranteed. High utilization can leave insufficient liquidity for a full exit until borrowers repay or new suppliers enter.
Overcollateralization can reduce borrower credit risk without eliminating smart contract, oracle, governance or administrator-key risk. A software error, manipulated price input or compromised privileged account can cause a loss independently of borrower solvency.
Institutional lending
Institutional products may lend stablecoins to market makers, trading firms or other businesses. Yield comes from interest paid by those borrowers. The critical questions are whether the loan is secured, what collateral is accepted, how frequently it is valued, who controls it and how the lender can enforce its claim after default.
Higher rates can reflect borrower risk, collateral weakness, concentration, a fixed term or limited withdrawal rights. A finance team should not treat the provider’s interface as evidence that the underlying exposure is diversified or readily recoverable.
Trading and liquidity strategies
Other products seek returns from funding-rate differences, basis trades, market making or liquidity provision. Terms such as market-neutral describe the strategy’s objective, not a guarantee against loss. Leverage, execution failures, exchange exposure and a breakdown in expected price relationships can all affect repayment.
Comparison of stablecoin yield sources
| Source | How return is generated | Liquidity mechanics | Primary risks | Evidence to request |
|---|---|---|---|---|
| Government security or money market exposure | Interest from short-duration securities, less fees | Usually subject to dealing cutoffs, business days and settlement terms | Legal structure, issuer, custodian, banking and redemption risk | Offering documents, asset reports, fee schedule and redemption policy |
| Onchain lending | Interest paid by borrowers using a lending pool | Blockchain settlement, subject to network operation and available pool liquidity | Smart contract, oracle, governance, utilization and stablecoin risk | Contract addresses, administrator powers, market utilization and security reviews |
| Institutional lending | Interest paid by a trading firm or other borrower | May involve notice periods, withdrawal windows or fixed maturity | Default, collateral, concentration, custody and recovery risk | Borrower identity, collateral terms, financial information and default provisions |
| Trading or liquidity strategy | Spreads, funding payments, trading gains or liquidity fees | Depends on the ability to close positions and withdraw from venues | Market, leverage, execution, exchange and strategy risk | Strategy description, leverage limits, venue exposure and loss history |
How to compare quoted yield
Rates should be placed on a consistent basis before comparison. Determine whether each figure is an annual percentage rate or an annual percentage yield, whether compounding is assumed, and whether the displayed number is a current variable rate or a rate fixed for a defined term.
Finance teams should also confirm whether the quote is gross or net of management fees, performance fees, conversion spreads and withdrawal charges. Network transaction costs may sit outside the displayed yield but still reduce the company’s realized return.
Check the payment asset. Yield paid in USDC or USDT differs from promotional rewards paid in a separate token whose market price and liquidity can change. A headline rate that includes volatile incentives should be separated into base interest and token rewards. Treasury forecasts should not treat an unsold reward token as an assured dollar return.
Document withdrawal terms as operational facts
Words such as instant, liquid and flexible are not adequate for treasury planning. Record the complete path from submitting a redemption to receiving spendable funds.
- Dealing frequency: continuously, at scheduled intervals, on business days or only at maturity.
- Notice and cutoff: when a request must be submitted and which time zone governs it.
- Settlement: when the stablecoin or fiat is contractually due after acceptance.
- Liquidity dependency: whether payment relies on cash reserves, secondary-market depth, asset sales or borrower repayment.
- Limits and costs: minimum balances, redemption caps, conversion charges, network fees and early-exit costs.
- Suspension rights: who can pause withdrawals, under what conditions and for how long under the governing documents.
- Return route: the approved wallet, blockchain network or bank account that will receive proceeds.
Network details are part of liquidity. Native USDC on one network is operationally different from USDC on another network, and a bridged token can introduce an additional bridge or issuer-recognition risk. If proceeds arrive on a network that the company cannot use for payroll, vendors or fiat conversion, the treasury team must account for the extra transfer, conversion and approval steps.
Perform legal, custody and technical diligence
A provider’s dashboard balance does not by itself establish ownership. Finance and legal teams should identify whether assets remain in a company-controlled wallet, enter a segregated account, become fund property or create an unsecured claim against the provider or borrower.
For onchain products, record the exact contract and token addresses rather than relying only on asset symbols. Review who can upgrade contracts, change parameters, freeze activity or move funds. External security reviews can inform diligence, but they do not guarantee that a contract is free from defects.
For offchain products, identify the contracting entity, governing law, custodian, underlying borrower and the company’s position if an intermediary becomes insolvent. Asset reports or reserve attestations can support the review, but they do not replace analysis of the legal claim or withdrawal provisions.
Size the allocation from cash needs, not the advertised rate
Begin with funds available after known obligations and a board- or management-approved operating buffer:
Eligible amount = liquid treasury − forecast outflows − operating buffer − restricted balances
If a company has $1 million in stablecoins, expects $300,000 of near-term payments and maintains a $200,000 contingency buffer, no more than $500,000 is initially eligible for yield consideration. The final allocation may be lower after considering redemption, stablecoin, counterparty and concentration risks.
The eligible balance can then be divided into liquidity tiers:
- Immediate operations: same-day payroll, vendors, cards, taxes and unexpected payments.
- Short reserve: funds placed only where documented redemption timing matches the cash forecast.
- Longer reserve: funds the company can tolerate being unavailable through a defined term or disruption.
Stress the plan before approving it. Combine adverse events rather than testing them separately: delayed customer receipts, higher operating expenses, a stablecoin trading below its target value and a suspended redemption. If the remaining liquid treasury cannot cover the combined scenario, the proposed allocation is too large.
Apply treasury controls and maintain audit evidence
A yield allocation should be controlled like any other treasury movement. The approval record should identify the amount, destination address, network, product, yield source, expected withdrawal timing and authorized signers.
- Verify the legal entity, eligibility requirements and governing documents.
- Document the return source, all fees and whether the rate can change.
- Confirm the destination address and network through an independent check.
- Use approval and signing quorum appropriate to the amount and risk.
- Test a small allocation and redemption before increasing exposure.
- Set review dates for rates, utilization, counterparties and withdrawal availability.
- Reconcile principal, income, fees and network costs to statements and transaction records.
Accounting treatment depends on the instrument and applicable standards. Records should nevertheless distinguish the original stablecoin balance, assets exchanged or deposited, yield accrued or received, provider fees, token rewards, valuation changes and realized gains or losses. Preserve transaction hashes, approvals, statements and redemption confirmations as audit evidence.
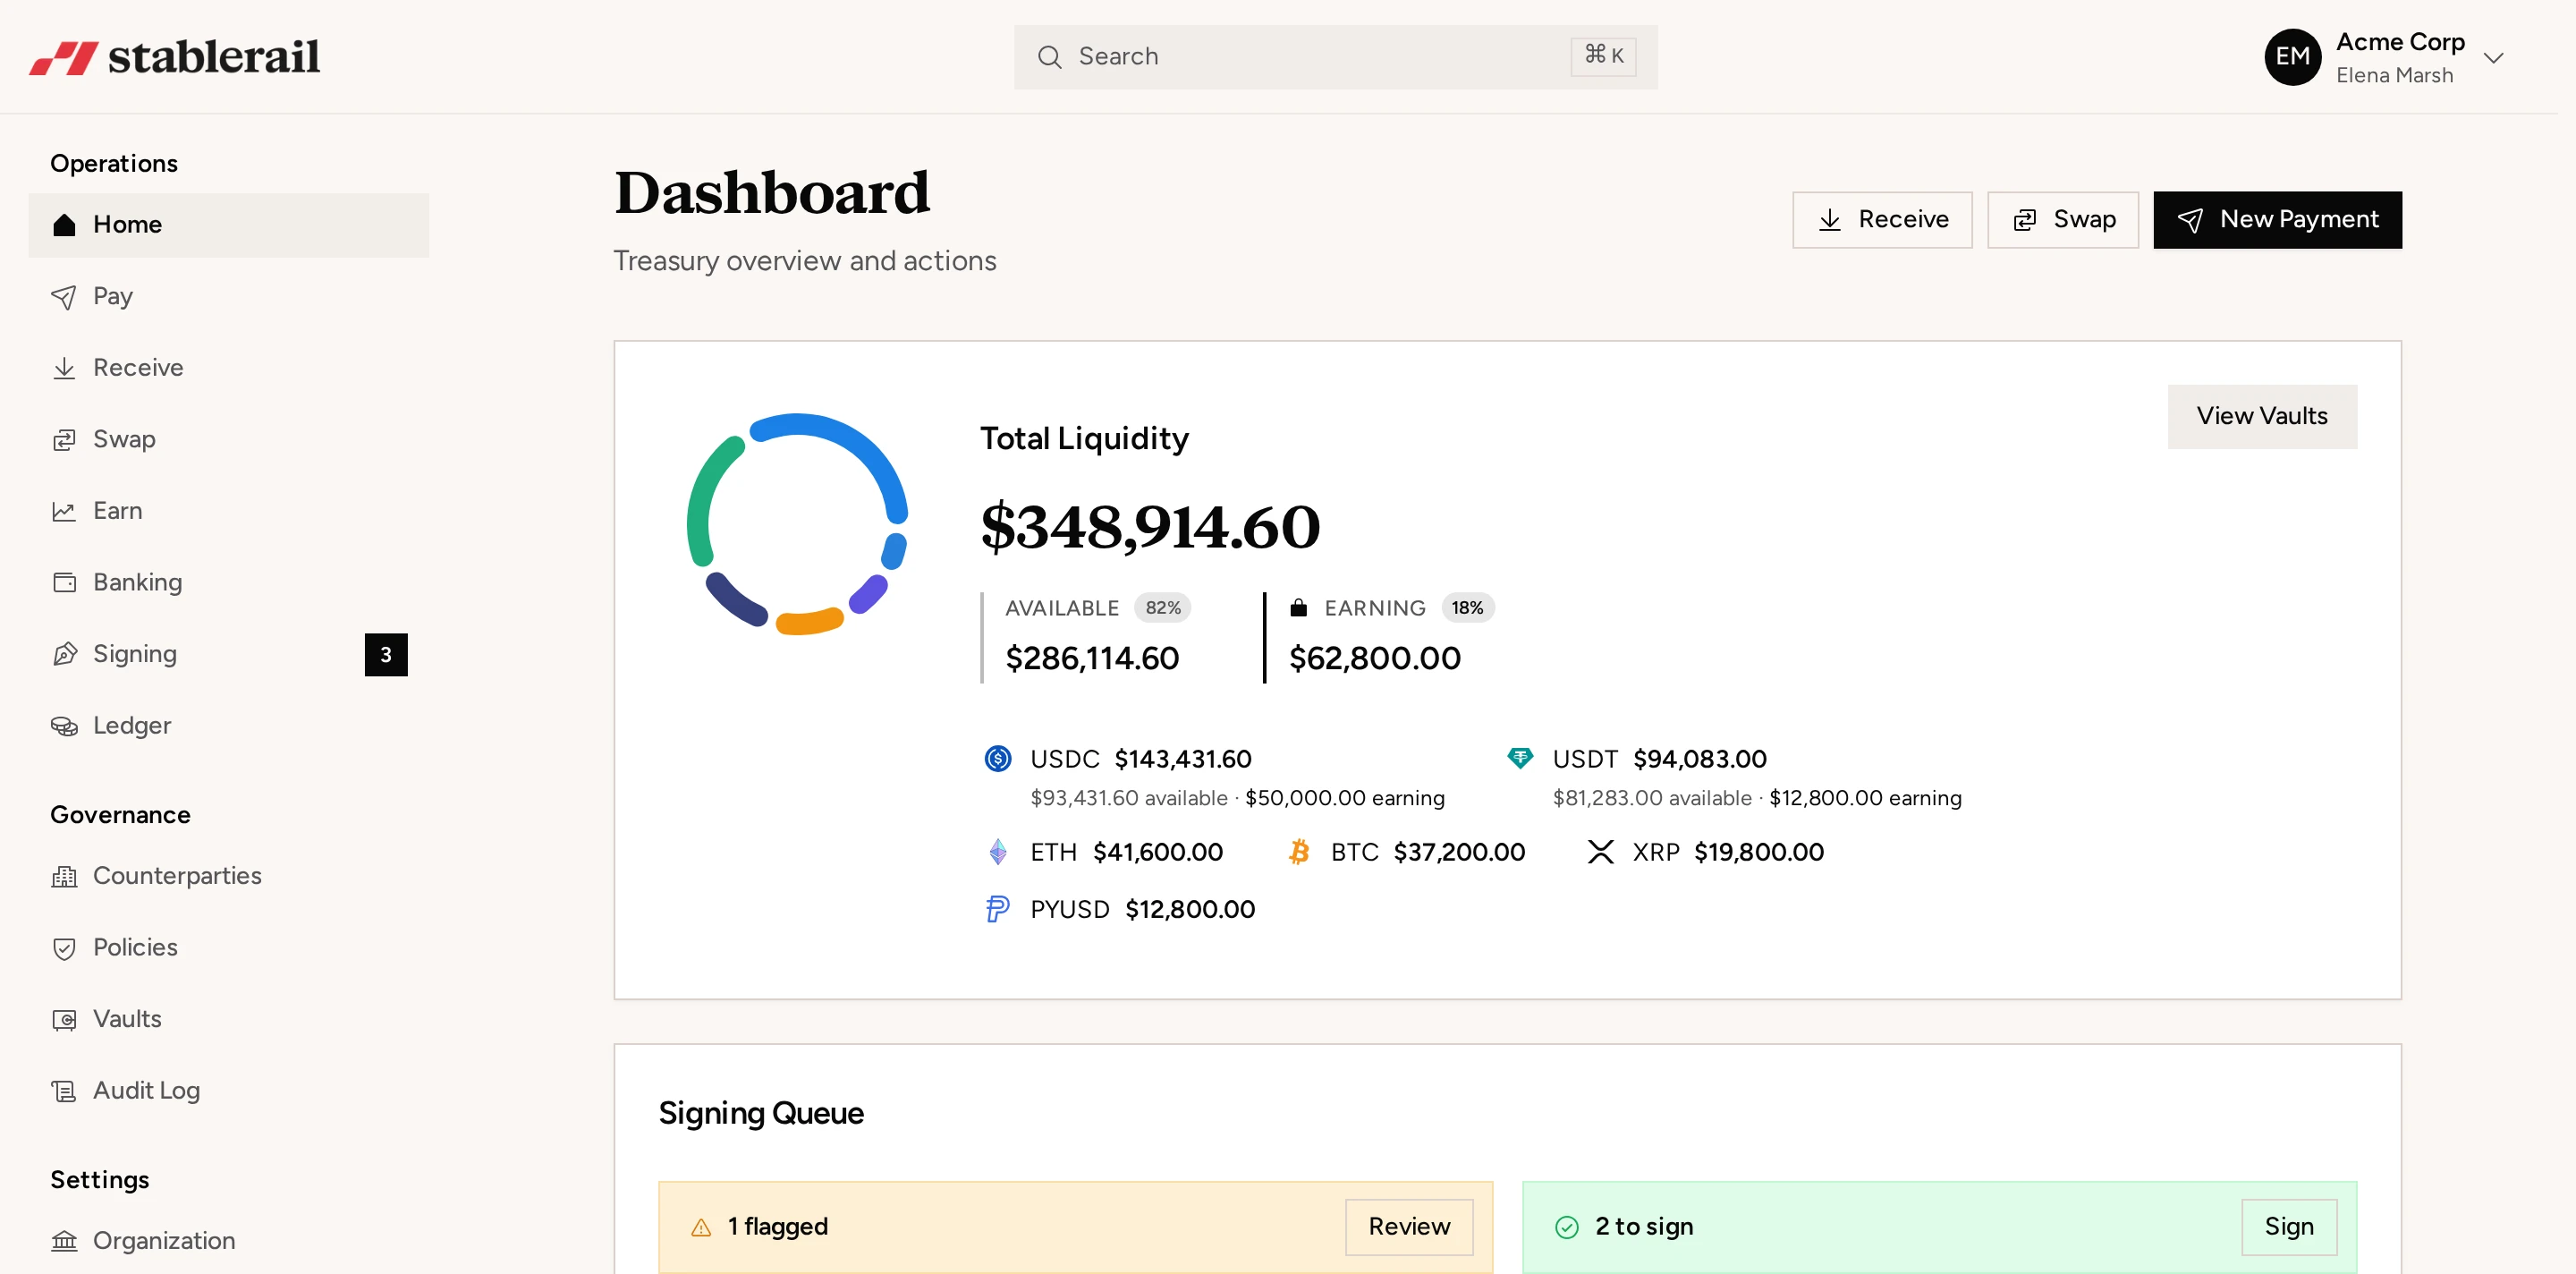
Stablerail can support the operating-control layer for a company’s own USDC and USDT through approvals and signing quorum, sanctions and address screening before sends, fiat conversion and exportable audit evidence. Those controls do not replace diligence on the separate yield product or its underlying exposure.
The objective is not to maximize every basis point. It is to earn a defensible return on genuinely idle funds without impairing payroll, supplier payments, tax obligations or the company’s ability to respond to market stress.
Frequently asked questions
What is the safest way for a company to earn yield on USDC?
No USDC yield product is risk-free. Products backed by short-duration government securities may have a more transparent return source, but finance teams must still assess the legal structure, custody chain, fees, eligibility and redemption process.
Does USDC automatically earn interest in a corporate wallet?
No. USDC normally earns no interest simply by sitting in a wallet. The company must allocate or exchange it into a lending, securities or trading product, which introduces additional risks and liquidity terms.
Can a company withdraw from an onchain lending market at any time?
A withdrawal may be submitted at any time if the protocol and network are operating, but immediate completion is not guaranteed. High pool utilization, contract pauses, network disruption or insufficient available liquidity can delay an exit.
How much stablecoin treasury should be allocated to yield?
Start with total liquid treasury and subtract forecast outflows, an operating buffer and restricted balances. The resulting amount is only an initial ceiling; it should be reduced further for stress scenarios, concentration limits and uncertain redemption timing.
How should stablecoin yield be recorded for accounting purposes?
The treatment depends on the product’s legal form and the accounting standards that apply to the company. At minimum, records should separately track principal, accrued or received income, fees, token rewards, network costs and valuation changes, supported by statements and blockchain transaction evidence.
Finance writers covering stablecoin treasury, payments, compliance, and risk controls.
More about the Stablerail team- Stablecoin treasury managementApprovals, limits, yield and reporting on one balance.
- Stablecoin payoutsBatch contractor and vendor payments with screening.
- USDT vs USDCWhich stablecoin your company should settle in.
- Stablecoin finance glossaryMPC, off-ramp, travel rule and the rest, in plain English.
- Product updatesEverything we ship, month by month.